
Credit and Debit Notes: How to Correct an E-Invoice After It Is Issued
Credit and debit notes are the only way to correct an e-invoice after it has been issued. Learn when to use each type, what it must contain and how to record the journal entries.
سامي الحيدري
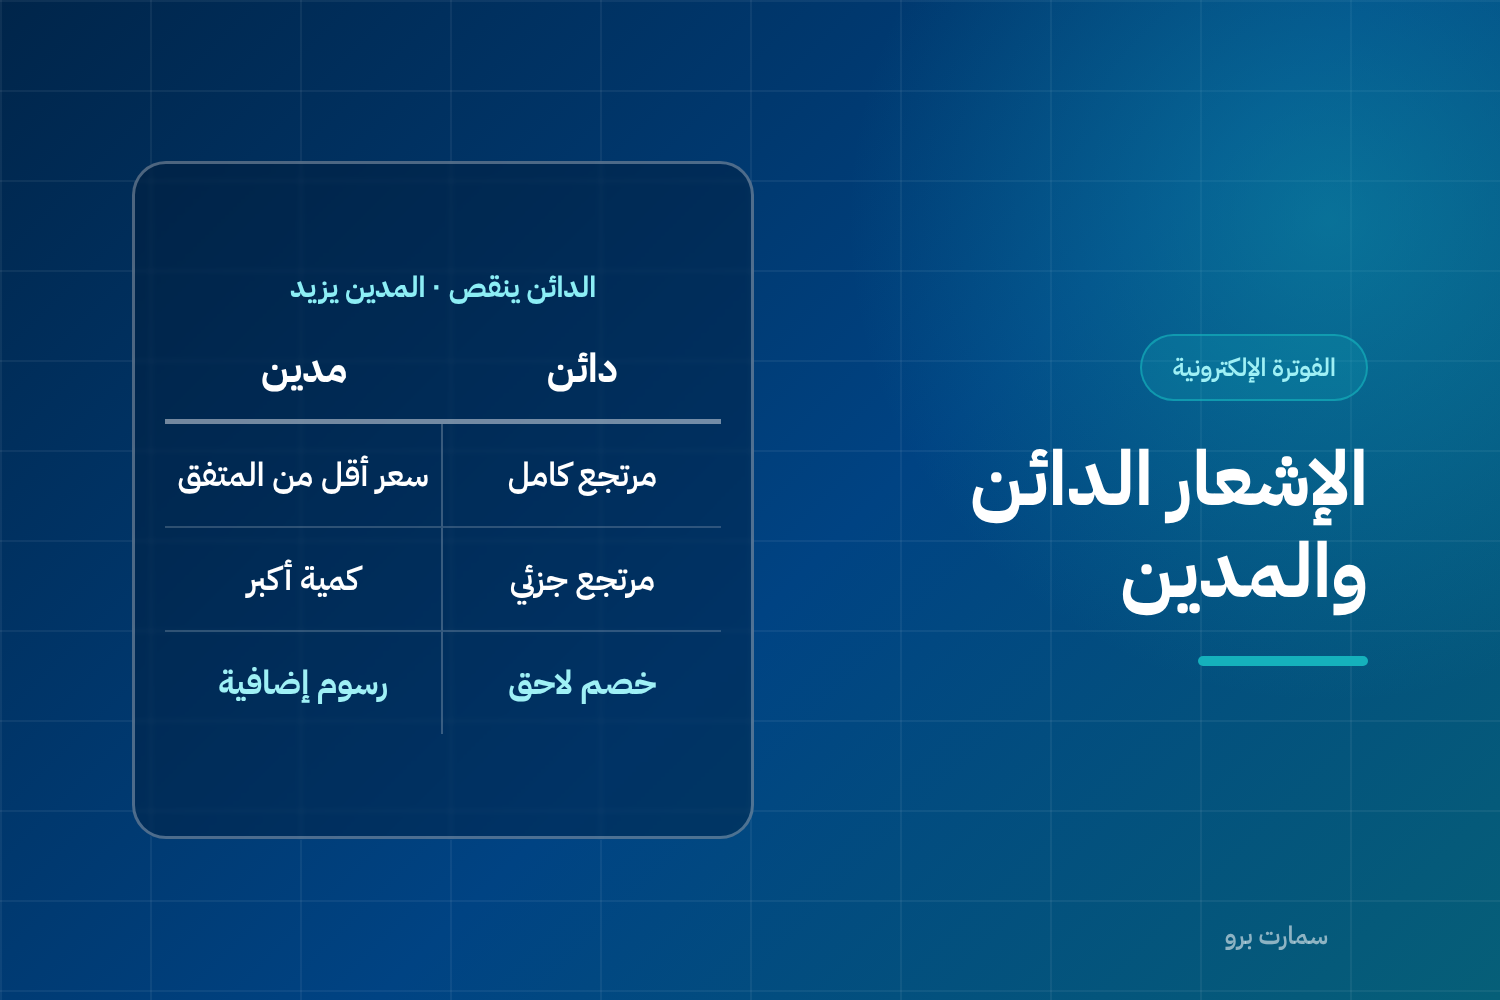
Under Phase 2 e-invoicing, credit and debit notes are the only way to correct an invoice that has already been issued. You can no longer edit or delete the invoice, because every invoice is a link in a chain that has been signed and sent to the Fatoora platform.
The idea is simple: the incorrect invoice stays as it is, and a new document is issued to adjust its effect.
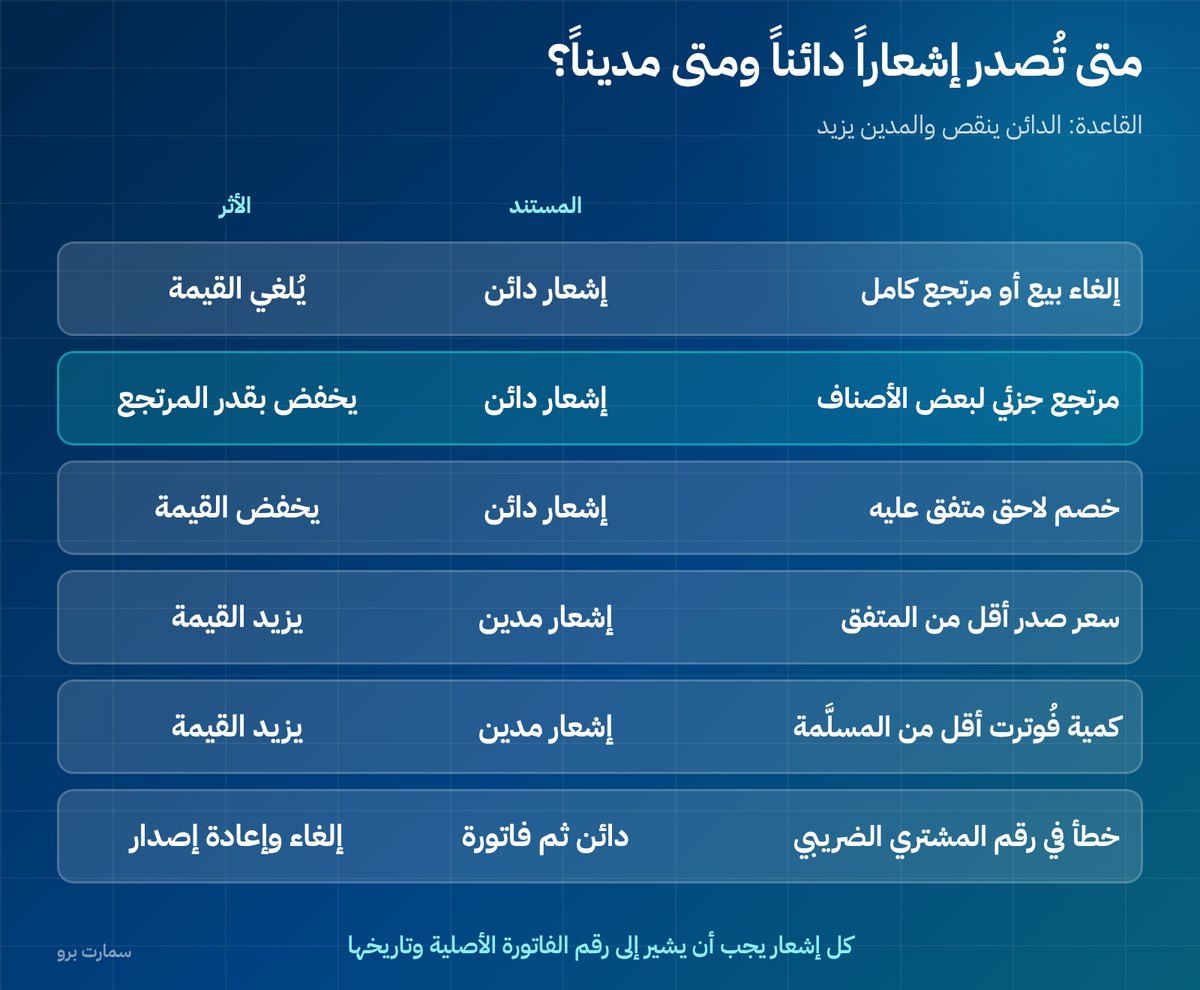
Credit and debit notes: which one do you issue?
| Situation | Document | Effect |
|---|---|---|
| Cancelled sale or full return | Credit note | Cancels the invoice value |
| Partial return of some items | Credit note | Reduces the value by the returned amount |
| Agreed discount granted later | Credit note | Reduces the value |
| Price invoiced lower than agreed | Debit note | Increases the value |
| Quantity invoiced lower than delivered | Debit note | Increases the value |
| Additional charges due | Debit note | Increases the value |
| Error in the buyer's VAT number | Credit note, then a new invoice | Cancel and reissue |
The rule that sums up the table: a credit note reduces, a debit note increases. And if the error is in the buyer's details rather than the amount, the fix is a full cancellation with a credit note followed by a correct new invoice.
What must a credit or debit note contain?
A note is a complete electronic document that follows the same path as an invoice: it is signed, sent, and either cleared or reported depending on its type.
The most important element is the link to the original invoice: its number and date. A note floating in the air with no reference is hard to trace and loses its meaning during an audit.
It also needs a clear reason for issue. Don't write "correction"; write "return of two items from invoice no. X" or "agreed discount of 5%".
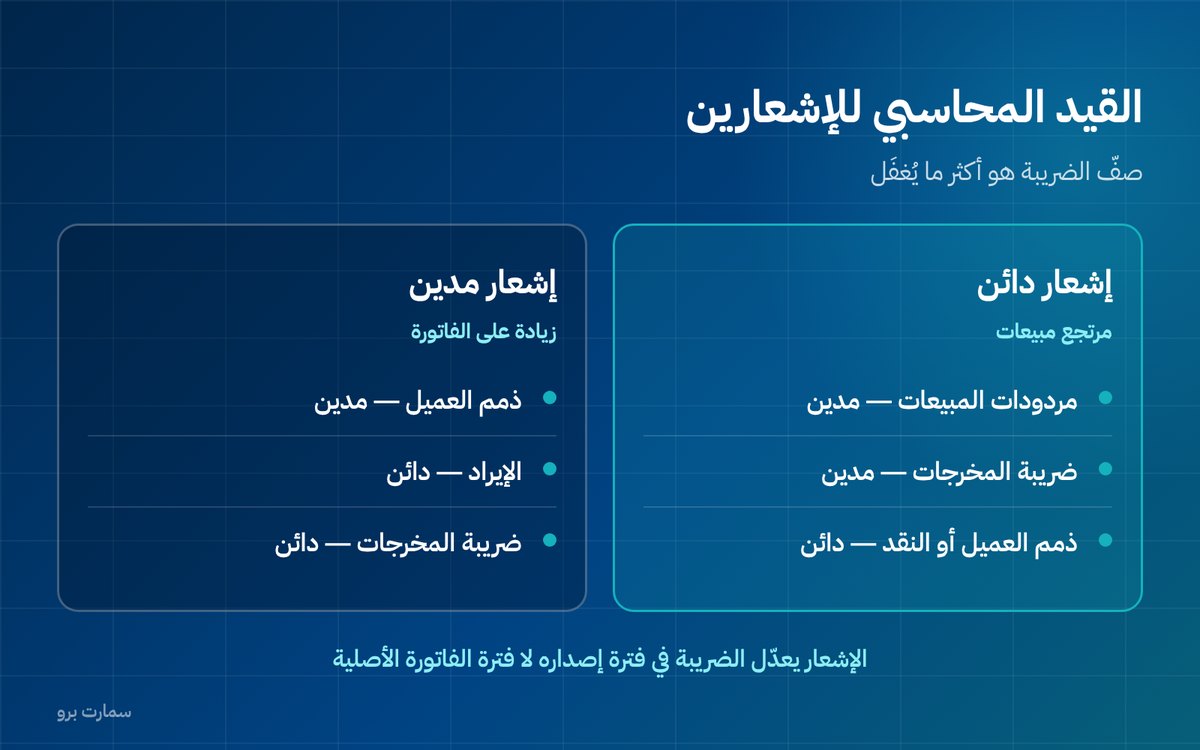
What are the journal entries for each note?
Credit note (sales return):
- Debit sales returns with the value of the goods.
- Debit output VAT with the VAT being reversed.
- Credit the customer's receivable or cash with the total.
Debit note (increase on the invoice):
- Debit the customer's receivable with the new total.
- Credit revenue with the amount of the increase.
- Credit output VAT with the VAT on the increase.
Watch the VAT line in both cases. Leaving it out is the most common accounting error with notes, and it creates a gap between your books and your VAT return that surfaces at the end of the quarter.
How does a note affect the VAT return?
A note adjusts the VAT due in the period in which it is issued, not the period of the original invoice. So a credit note issued in April against a January invoice reduces output VAT in the second-quarter return, not the first.
This means that delaying a note delays recovering what you are owed. If the return is large, the difference between issuing it at the end of one month or the start of the next shifts your cash flow by a full quarter.
How do notes work at the point of sale in restaurants and retail?
In retail and restaurants, cancellations and returns happen dozens of times a day. The common mistake is for the cashier to cancel the invoice on screen and assume it has disappeared.
Under Phase 2, if the invoice has actually been issued and printed, cancelling it on screen does not remove it from the chain. What is required is a credit note, issued and reported exactly like the invoice.
That is why you should ask your vendor one specific question: how many taps does a cashier need to issue a credit note? If the answer is more than three, staff will find worse ways around it.
Set a clear rule: cancelling before printing is one thing, and cancelling after printing is something else entirely.
Should you cancel the whole invoice for a partial return?
Another recurring mistake: a customer returns one item from an invoice with ten items, and the employee issues a credit note for the full invoice value, then a new invoice for the remaining nine.
This produces three documents instead of one and inflates the sales and returns figures in your reports for no reason. The correct approach is a credit note for the returned item and its VAT only, referencing the original invoice.
What are the five most common mistakes?
- Editing the original invoice in the system instead of issuing a note. This breaks consistency between your books and what was sent to the platform.
- A note with no reference to the original invoice, which makes tracing it during an audit almost impossible.
- Leaving out VAT in the note's journal entry, which builds up a growing difference in the output VAT account.
- Issuing a credit note for more than the original invoice without a documented justification.
- Using notes as a monthly marketing discount tool instead of including the discount in the invoice from the start.
Why should you monitor the ratio of notes to invoices?
Notes are not a problem in themselves, but their ratio is an indicator. If credit notes exceed a certain share of your invoices each month, the cause is usually not normal returns but a recurring issuing error: outdated prices, staff issuing the wrong type, or items priced incorrectly in the system.
Run a monthly report of notes grouped by reason and by employee. That report alone shows where the errors are leaking in.
When do you not need a note?
If the error is discovered before the tax invoice is cleared and delivered, no note is needed: correct it and resubmit. This is exactly why you should never hand the buyer a copy before clearance.
A simplified invoice, however, counts as issued the moment it is handed to the customer, and any correction after that is made with a note.
The detailed requirements for notes, when they are issued and what they must contain are published by the Zakat, Tax and Customs Authority (ZATCA).
Key takeaway: Never edit or delete an issued e-invoice: issue a credit note to reduce it or a debit note to increase it, always referencing the original invoice and including the VAT line.
Read also
- Invoice rejection errors and how to fix each one
- Standard tax invoice vs simplified invoice
- Journal entries: how to write one step by step
To see how SmartPro issues Fatoora-ready credit notes from the POS and posts their entries automatically, start a free trial.
Frequently asked questions
What is the difference between a credit note and a debit note?
A credit note reduces the value of an invoice and is used for returns, cancellations and discounts granted after the sale. A debit note increases the value and is used when the price was invoiced lower than agreed, a smaller quantity was invoiced than delivered, or additional charges become due.
Can an e-invoice be edited after it is issued?
No. Once issued, the invoice is part of a chain that has been signed and sent to the Fatoora platform, and editing it would break that chain. The only accepted correction is to issue a credit or debit note linked to the original invoice by its number and date.
What is the journal entry for a credit note?
Debit sales returns with the value of the goods, debit output VAT with the VAT being reversed, and credit the customer's receivable or cash with the total. Leaving out the VAT line is the most common mistake and creates a difference between the books and the VAT return.
In which period does a note affect the VAT return?
A note affects the period in which it is issued, not the period of the original invoice. A credit note issued in April against a January invoice reduces output VAT in the second-quarter return, which is why delaying it delays recovering what you are owed.