
Retirement Benefit Plan Financial Statements: IAS 26
How retirement benefit plans prepare their financial statements under IAS 26, and how a defined contribution plan differs from a defined benefit plan.
Author:سامي الحيدري
Retirement benefit plans raise two separate questions that are often confused. The first is how the employer accounts for the cost of employee benefits. The second is how the plan itself prepares its financial statements. The first belongs to IAS 19 on employee benefits. The second belongs to IAS 26.
IAS 26 sets the minimum content of the financial statements of retirement benefit plans whenever such statements are prepared. It treats the plan as a reporting entity separate from the employers whose employees take part in it. It deals with reporting to participants as a group, not with individual benefit statements.
Which retirement benefit plans fall under IAS 26?
The standard applies to the financial statements of retirement benefit plans, covering both defined contribution plans and defined benefit plans. It applies whether or not a separate fund exists, and whether or not trustees are appointed. Plans whose assets are invested with insurance companies are in scope, except where the contract is in the name of a specific participant or group of participants and the insurer alone carries the obligation.
The following are excluded:
- End-of-service benefits.
- Deferred compensation arrangements.
- Long-service leave benefits.
- Special early retirement or redundancy plans.
- Health and welfare plans.
- Bonus plans.
- Government social security arrangements.
That last exclusion matters in the Saudi context: the financial statements of the General Organization for Social Insurance (GOSI) are not the subject of this standard.
What are the three key definitions?
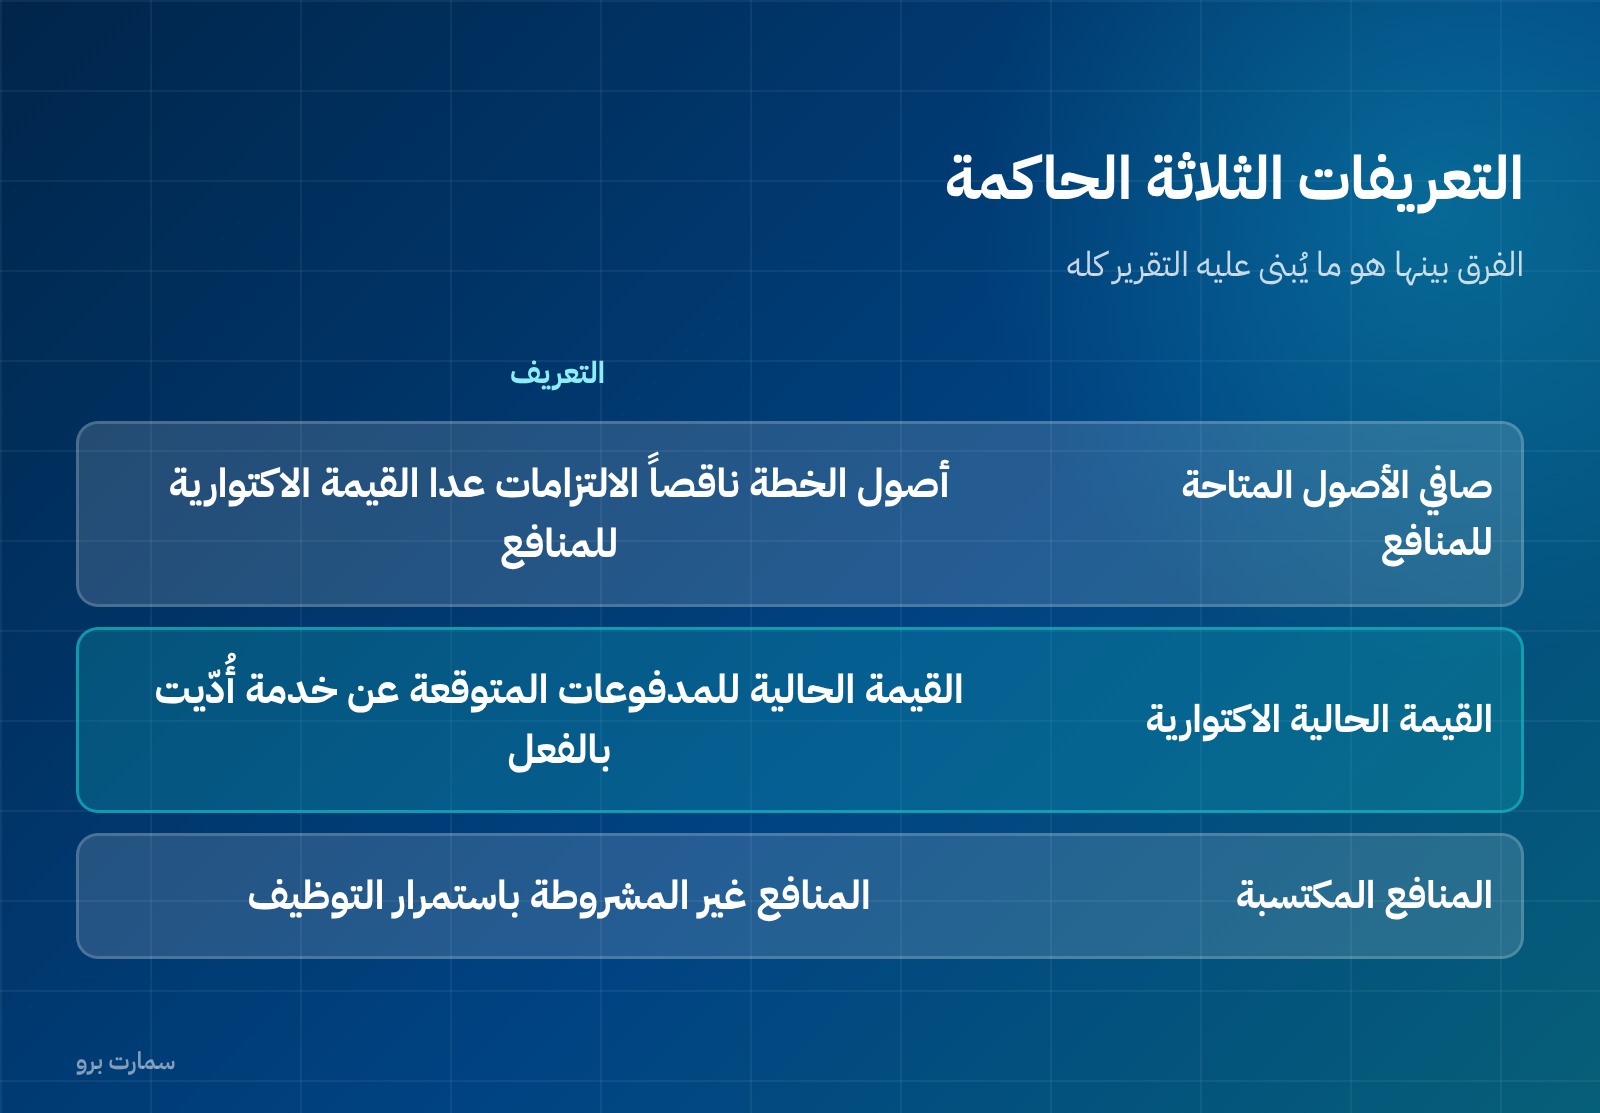
| Term | Definition |
|---|---|
| Net assets available for benefits | The plan's assets less its liabilities, other than the actuarial present value of promised retirement benefits |
| Actuarial present value of promised retirement benefits | The present value of the payments the plan expects to make for service already rendered |
| Vested benefits | Benefits that are not conditional on continued employment |
What must a defined contribution plan report?
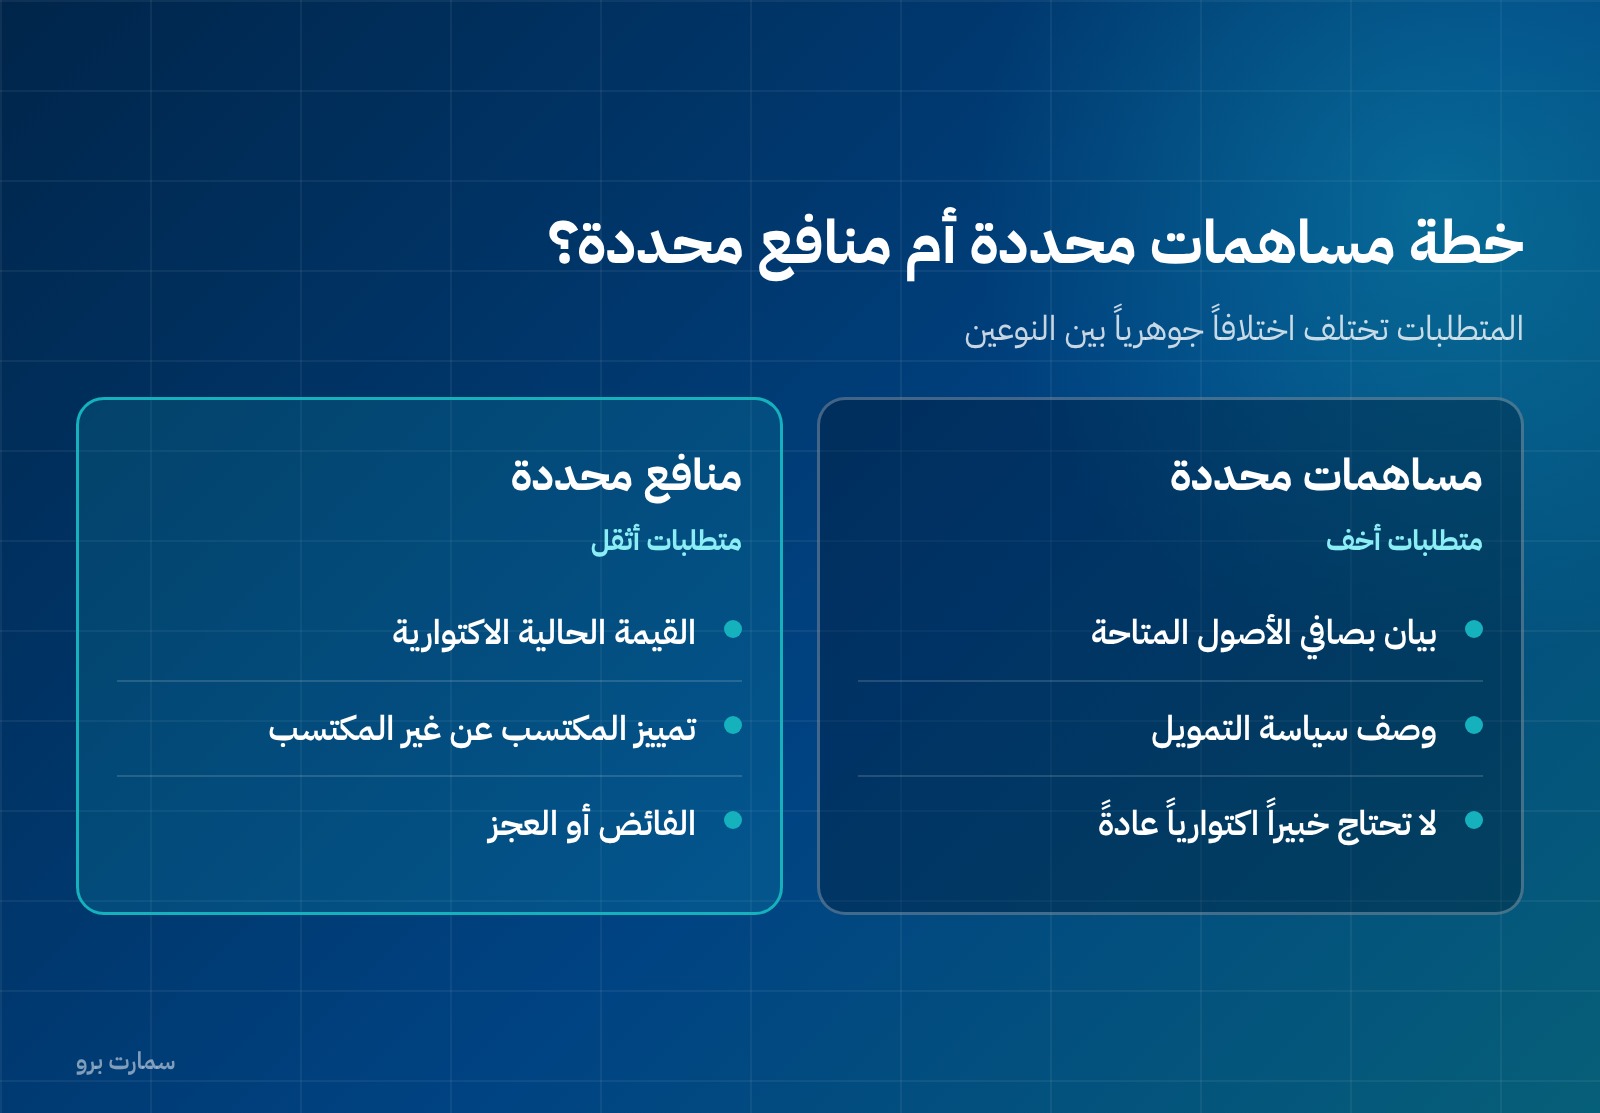
A defined contribution plan is one where the employer pays fixed contributions and the benefit depends on what those contributions and their investment returns build up. Its requirements are lighter. The financial statements must include a statement of net assets available for benefits and a description of the funding policy.
The aim is periodic reporting on the plan and its investment performance. This is usually achieved through a description of significant activities and the effect of any changes to the plan, its membership or its terms; statements of transactions, investment performance and the financial position at the end of the period; and a description of investment policies.
Such a plan usually does not need an actuary, because the employer's obligation ends once the contribution is paid.
What are the two options for a defined benefit plan?
A defined benefit plan is one where the benefit is promised in advance, usually by a formula based on salary and years of service. This is the central point of the standard. The financial statements must contain one of two things.
Option one: a single statement showing all three of the following together:
- Net assets available for benefits.
- The actuarial present value of promised retirement benefits, distinguishing between vested and non-vested benefits.
- The resulting surplus or deficit.
Option two: a statement of net assets available for benefits, accompanied either by a note disclosing the actuarial present value (split into vested and non-vested), or by a reference to that information in an accompanying actuarial report.
If no actuarial valuation was prepared at the reporting date, the most recent valuation is used as the basis and its date is disclosed.
What actuarial basis is used?
The actuarial present value is based on the benefits promised for service rendered to date, using either current salary levels or projected salary levels. The basis used must be disclosed, because the difference between the two can change the figure significantly.
The statements must also disclose significant changes in actuarial assumptions and explain the relationship between the actuarial present value, the net assets available for benefits and the funding policy. The standard notes that in many countries actuarial valuations are carried out at least every three years.
How are hybrid plans and informal arrangements treated?
Three practical rules apply. A plan may be funded by parties other than employers. Informal plans are accounted for in the same way as formal ones. Hybrid plans are treated as defined benefit plans. The legal form of the arrangement does not change its accounting treatment.
What does a plan report contain in practice?
The standard recommends that a plan's report include elements that recur in practice:
- A statement of changes in net assets available for benefits: contributions received from employers and from participants, investment income, benefits paid and administrative expenses.
- A description of the plan: eligibility terms, the basis for calculating the benefit, and the number of active and retired participants.
- The investment policy, the allocation of assets across classes, and the performance of each class.
- The fair value of plan assets, since plan investments are usually measured at fair value. Fair value is the price that would be received to sell an asset in an orderly transaction between market participants.
What does a reader of these statements look for?
One question: are the plan's assets enough to meet what has been promised? That is why disclosing the surplus or deficit, meaning the difference between net assets available and the actuarial present value of promised benefits, is the heart of the whole report. A deficit does not necessarily mean something is wrong, but it calls for clarity on the funding policy and on the plan to close the gap.
How are plans funded through insurance companies treated?
Plans whose assets are invested with an insurance company are within the scope of the standard, on one condition: the contract must not be in the name of a specific participant or group of participants with the insurer alone carrying the obligation. If it is, the plan falls outside the scope, because the risk has passed entirely to the insurer and the plan is no longer a real party to it.
This distinction rests on who actually bears the risk, not on the form or name of the arrangement.
Why does this matter in Saudi Arabia?
Most Saudi businesses do not have an independent retirement plan with its own financial statements. Their obligation is limited to the end-of-service benefit provision and GOSI contributions, all of which are dealt with under IAS 19, not this standard.
However, as savings funds and employee savings programmes expand in larger companies, entities appear whose money is managed independently and which need their own financial statements. At that point, IAS 26 becomes the reference, not IAS 19. For the wider picture of how the standards apply locally, see our complete guide to IFRS in Saudi Arabia.
The official text is on ifrs.org.
What is the official title adopted in Saudi Arabia?
The official title of this standard is "IAS 26: Accounting and Reporting by Retirement Benefit Plans". SOCPA adopted it with a Saudi modification: zakat was added alongside income tax in paragraph 35.
Reference: Saudi Organization for Chartered and Professional Accountants (SOCPA), the document endorsing IFRS for application in the Kingdom, updated on 1447/07/04 AH.
Key takeaway: IAS 26 governs the plan's own financial statements, while IAS 19 governs the employer's books; a defined benefit plan must show whether its net assets cover the actuarial present value of promised benefits.
If you want the employer side, including end-of-service provisions and GOSI, recorded automatically in your books, try SmartPro's Finance & Accounting with a free trial.
Article visuals
Frequently asked questions
What is the difference between IAS 26 and IAS 19?
IAS 19 governs how an employer accounts for the cost of employee benefits in its own financial statements. IAS 26 governs the financial statements of the retirement benefit plan itself, treating the plan as a separate reporting entity.
What must the financial statements of a defined contribution plan include?
They must include a statement of net assets available for benefits and a description of the funding policy, along with information on significant activities, investment performance and investment policies. Such a plan usually does not need an actuary.
What are the two options for the financial statements of a defined benefit plan?
The first option is a single statement showing net assets, the actuarial present value of promised benefits split into vested and non-vested, and the resulting surplus or deficit. The second is a statement of net assets accompanied by a note, or a reference to an accompanying actuarial report, disclosing the actuarial present value.
Does the end-of-service benefit fall within the scope of IAS 26?
No. End-of-service benefits are explicitly excluded from IAS 26, as are deferred compensation arrangements, health and welfare plans, bonus plans and government social security arrangements. In Saudi Arabia, the end-of-service provision is accounted for under IAS 19.
How often is an actuarial valuation carried out?
IAS 26 notes that in many countries actuarial valuations are carried out at least every three years. If no valuation was prepared at the reporting date, the most recent valuation is used as the basis and its date is disclosed.