
Periodic vs Perpetual Inventory: The Difference Is in the Books, Not the Warehouse
The difference isn't how you count stock but when you know your cost of sales. The formula with a SAR example, and why the periodic system absorbs shrinkage without you ever seeing it.
Author:سامي الحيدري
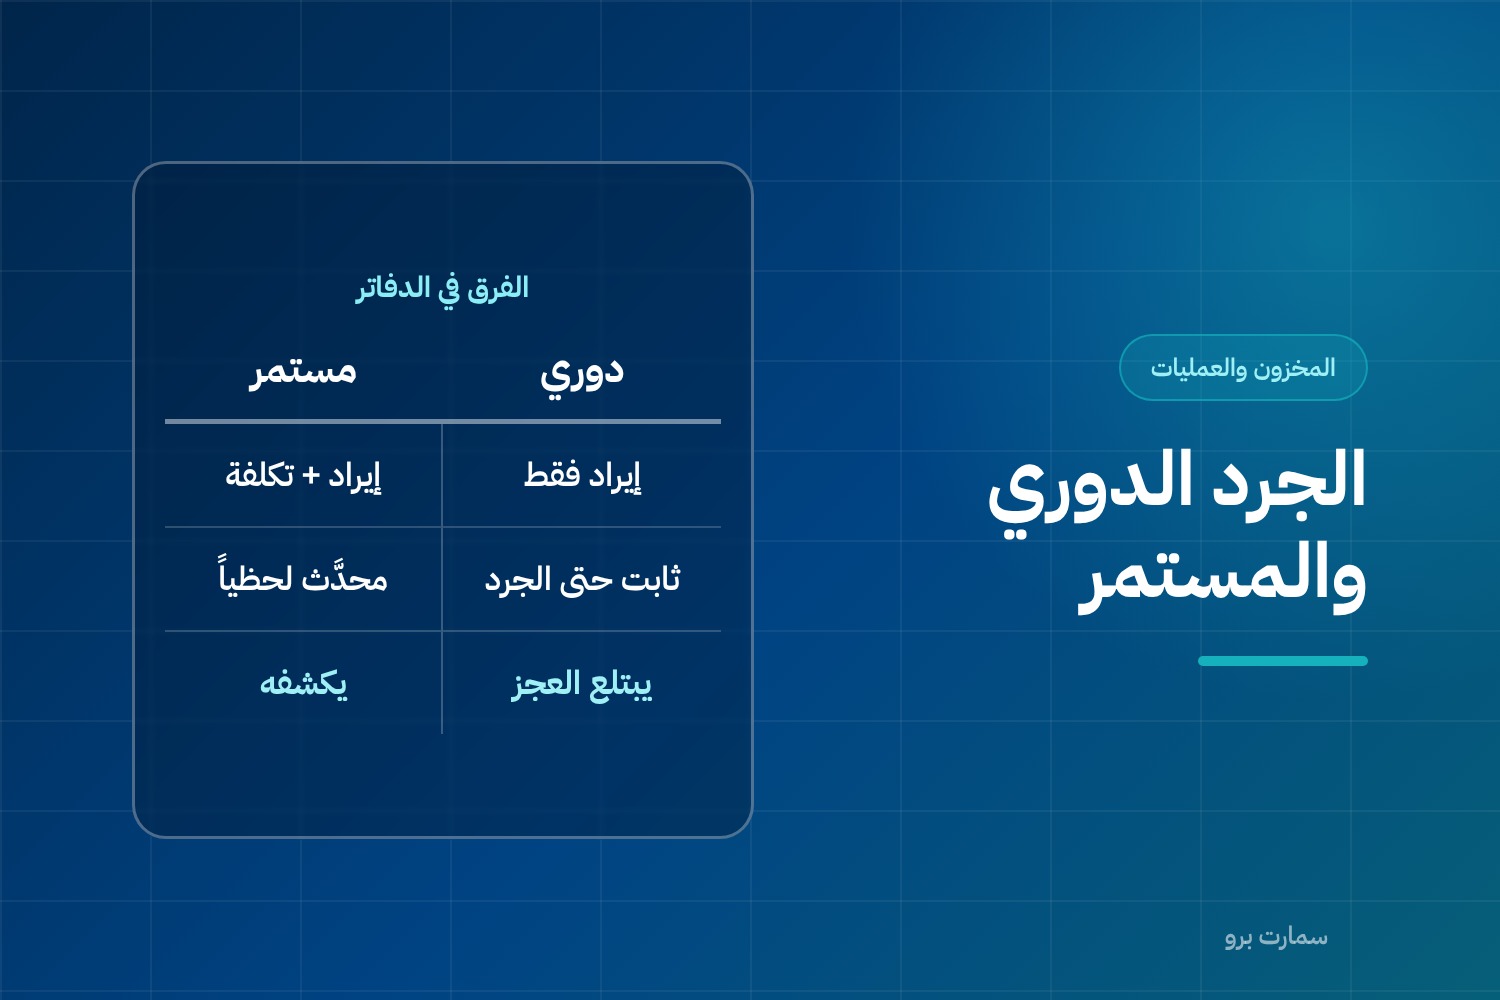
The choice between periodic vs perpetual inventory is not a choice between two ways of counting goods. They are two different systems for recording them in the books. What confuses most junior accountants is that the difference doesn't show up in the warehouse but in when you know your cost of sales: with every sale, or only at the end of the period.
The choice between them shapes your journal entries and what your system can tell you at any given moment.
Periodic vs perpetual inventory: the difference in one sentence
Under perpetual inventory, every sale produces two entries: one for the revenue, and one that takes the item out of inventory and charges it to cost of sales. The inventory account in the books is live and knows its balance at any moment.
Under periodic inventory, a sale produces only the revenue entry. Inventory stays at its opening value throughout the period, and cost of sales is known only after a physical count at period end, using the formula: opening inventory + purchases − closing inventory.
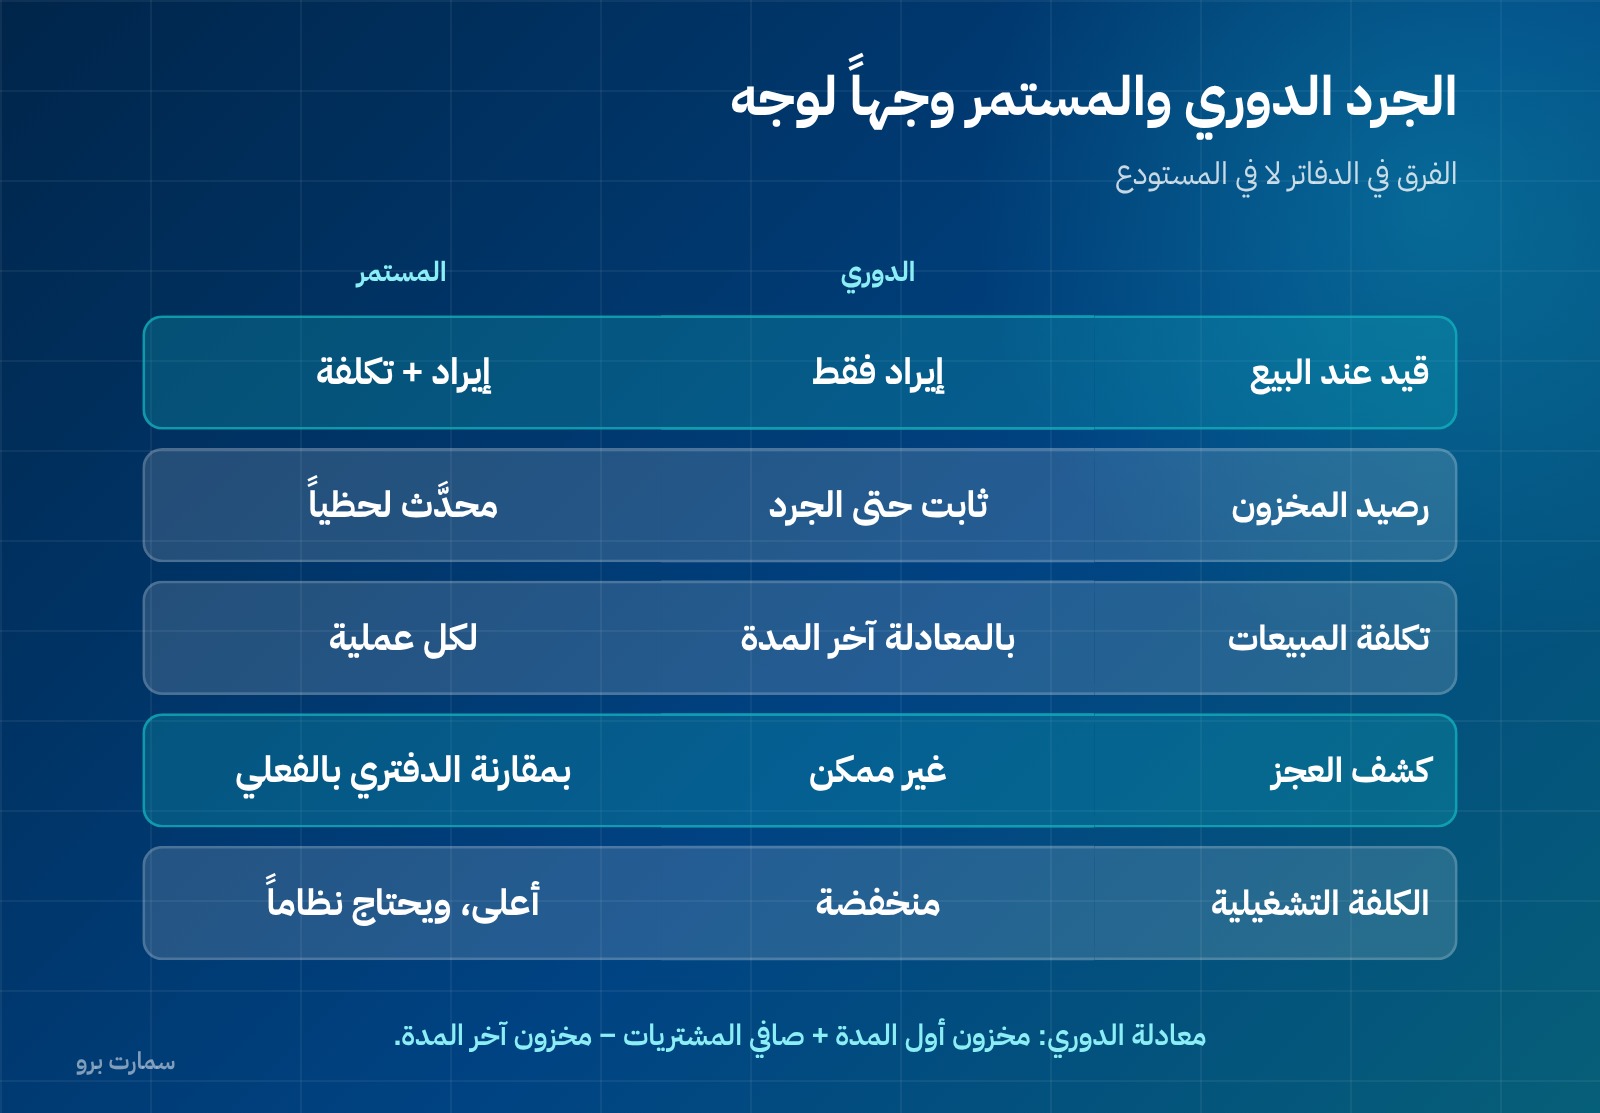
| Aspect | Periodic inventory | Perpetual inventory |
|---|---|---|
| Entry at the point of sale | Revenue only | Revenue + cost of sales |
| Inventory balance in the books | Unchanged until the count | Updated in real time |
| Cost of sales | Derived from the formula at period end | Known for every transaction |
| Detecting shortages and theft | Not possible | By comparing book and physical balances |
| Running cost | Low | Higher, and needs a system |
What formula is periodic inventory based on?
Cost of sales = opening inventory + net purchases − closing inventory
Net purchases = purchases + freight-in − purchase returns − discounts received.
A hypothetical example to illustrate the method: opening inventory is SAR 80,000, purchases during the year are SAR 460,000, freight-in is SAR 12,000, and purchase returns are SAR 8,000. The physical count at year end shows SAR 95,000.
Net purchases = 460,000 + 12,000 − 8,000 = SAR 464,000
Cost of sales = 80,000 + 464,000 − 95,000 = SAR 449,000
Notice the structural problem: this figure absorbs everything that left the warehouse, whether it was sold, stolen, damaged or lost. Shrinkage doesn't appear as a separate line; it disappears into cost of sales and reads as if it were goods sold. A business that lost SAR 5,000 of stock will never see that number. It will see a slightly thinner margin and won't know why.
What does perpetual inventory reveal that periodic doesn't?
With perpetual inventory you have two figures: the book balance from system transactions, and the physical balance from the count. The difference between them is the shortage or surplus, and it is recorded as a separate entry under its own name.
This, not accuracy alone, is the real reason to choose perpetual: it makes losses visible and accountable. A business running a warehouse with staff and daily movement that cannot measure count differences is operating without a gauge.
Perpetual inventory also adds operational capabilities: reorder points, out-of-stock alerts, and the profit margin on every invoice the moment it is issued. All of these depend on the system knowing the cost now, not three months later.
Does perpetual inventory remove the need to count?
A common mistake worth stating plainly: adopting perpetual inventory does not exempt you from physical counts. On the contrary, the physical count is the only thing that gives perpetual inventory its value, because it is what you compare the book balance against.
A business on perpetual inventory that never counts its goods has clean book figures that nothing corrects. That is more dangerous than periodic, because it creates confidence without a basis. Cycle counting by sample, one item or one shelf each week, works better in practice than a full annual count that shuts the business for two days.
How do the journal entries differ between the two systems?
On purchase:
- Perpetual: debit inventory, credit suppliers or cash. The purchase goes straight into the asset.
- Periodic: debit purchases (a temporary income-statement account, not an asset), credit suppliers. The inventory account is not touched.
On sale: perpetual records two entries. The first is for revenue (debit customers, credit sales and output VAT); the second is for cost (debit cost of sales, credit inventory). Periodic records the revenue entry alone.
At period end: periodic needs entries to close purchases and opening inventory and to record closing inventory, which are among the adjusting entries. Perpetual needs none of this, because its figures are ready, apart from the count-difference entry if there is one.
Here is a practical point often left out of the comparison: periodic looks cheaper, but it shifts the workload to period end, where it piles up alongside closing and review. Perpetual spreads the work across daily transactions that the system records anyway. So the saving in periodic is a saving in daily operations, not in total effort.
What are the signs that periodic inventory is no longer enough?
If any one of these three signs appears, the periodic system is costing you more than it saves:
- You only know your margin after closing. If the question "How much did we make this month?" requires a stock count, you are managing through the rear-view mirror.
- You sell what you don't have, or hold stock that doesn't move. A balance that isn't real-time produces both errors.
- You can't prove a loss. The warehouse keeper and the accountant blame each other, and there is no number to settle it.
Which inventory system suits your business?
Periodic is enough for a small business with few items, low unit values and no warehouse staff, such as a service shop holding some supplies. Its running cost is close to zero.
Perpetual is essential if any of these apply: many items, high unit values, more than one branch, staff handling the goods, or online sales that need an accurate real-time balance. In these cases perpetual is not an option but a requirement, and it calls for an inventory management system, not a spreadsheet.
Note an important overlap: the inventory system is one thing, and the inventory valuation method is another. Perpetual needs a valuation method that works in real time, such as moving average or cost layers, whereas periodic calculates it once at period end. The two questions are separate but answered together.
How do you move to the right system in three steps?
- Identify your current system: does a sale automatically produce a cost of sales entry? If not, you are on periodic, whatever the software is called.
- If you are on periodic and want to switch: start with a full physical count to serve as the opening balance, because perpetual is built on a correct starting point. The impact is explained in moving from one accounting system to another.
- Set a fixed cycle-count routine by sample, and record count differences with a separate entry, not a silent balance adjustment.
The rules for measuring inventory and presenting it in the financial statements come from the International Financial Reporting Standards.
In SmartPro, every system is connected, so a sale updates stock and accounts by itself; you can see how this works in SmartPro Inventory.
Key takeaway: Periodic inventory tells you cost of sales only after a count and hides shrinkage inside it; perpetual inventory knows the cost with every sale and, combined with regular physical counts, makes losses visible.
To see perpetual inventory running on your own items, start a free trial.
Article visuals
Frequently asked questions
What is the difference between periodic and perpetual inventory?
Under perpetual inventory, every sale produces two entries, one for revenue and one for cost of sales, so the inventory balance is updated in real time. Under periodic inventory, a sale produces only the revenue entry, inventory stays at its opening value, and cost of sales is known only after a physical count at period end.
What is the cost of sales formula under periodic inventory?
Cost of sales = opening inventory + net purchases − closing inventory. Net purchases = purchases + freight-in − purchase returns − discounts received.
Why doesn't periodic inventory reveal shortages and theft?
Because its formula absorbs everything that left the warehouse, whether sold, stolen, damaged or lost, so shrinkage disappears into cost of sales and reads as goods sold. Perpetual inventory gives you a book balance and a physical balance, and the difference between them is recorded as a separate entry under its own name.
Does perpetual inventory replace physical counting?
No. The physical count is what gives perpetual inventory its value, because it is what the book balance is compared against. A business on perpetual inventory that never counts its goods has book figures that nothing corrects, which is more dangerous than periodic because it creates confidence without a basis.
Which inventory system suits my business?
Periodic is enough for a small business with few items, low unit values and no warehouse staff. Perpetual is essential if any of these apply: many items, high unit values, more than one branch, staff handling the goods, or online sales that need an accurate real-time balance.