
Break-Even Point: The Formula, a SAR Example and Four Ways to Lower It
How many units must you sell to avoid a loss? The formula and its precondition, a full worked example in SAR, the margin of safety, and four practical ways to lower the number before you decide.
Author:سامي الحيدري
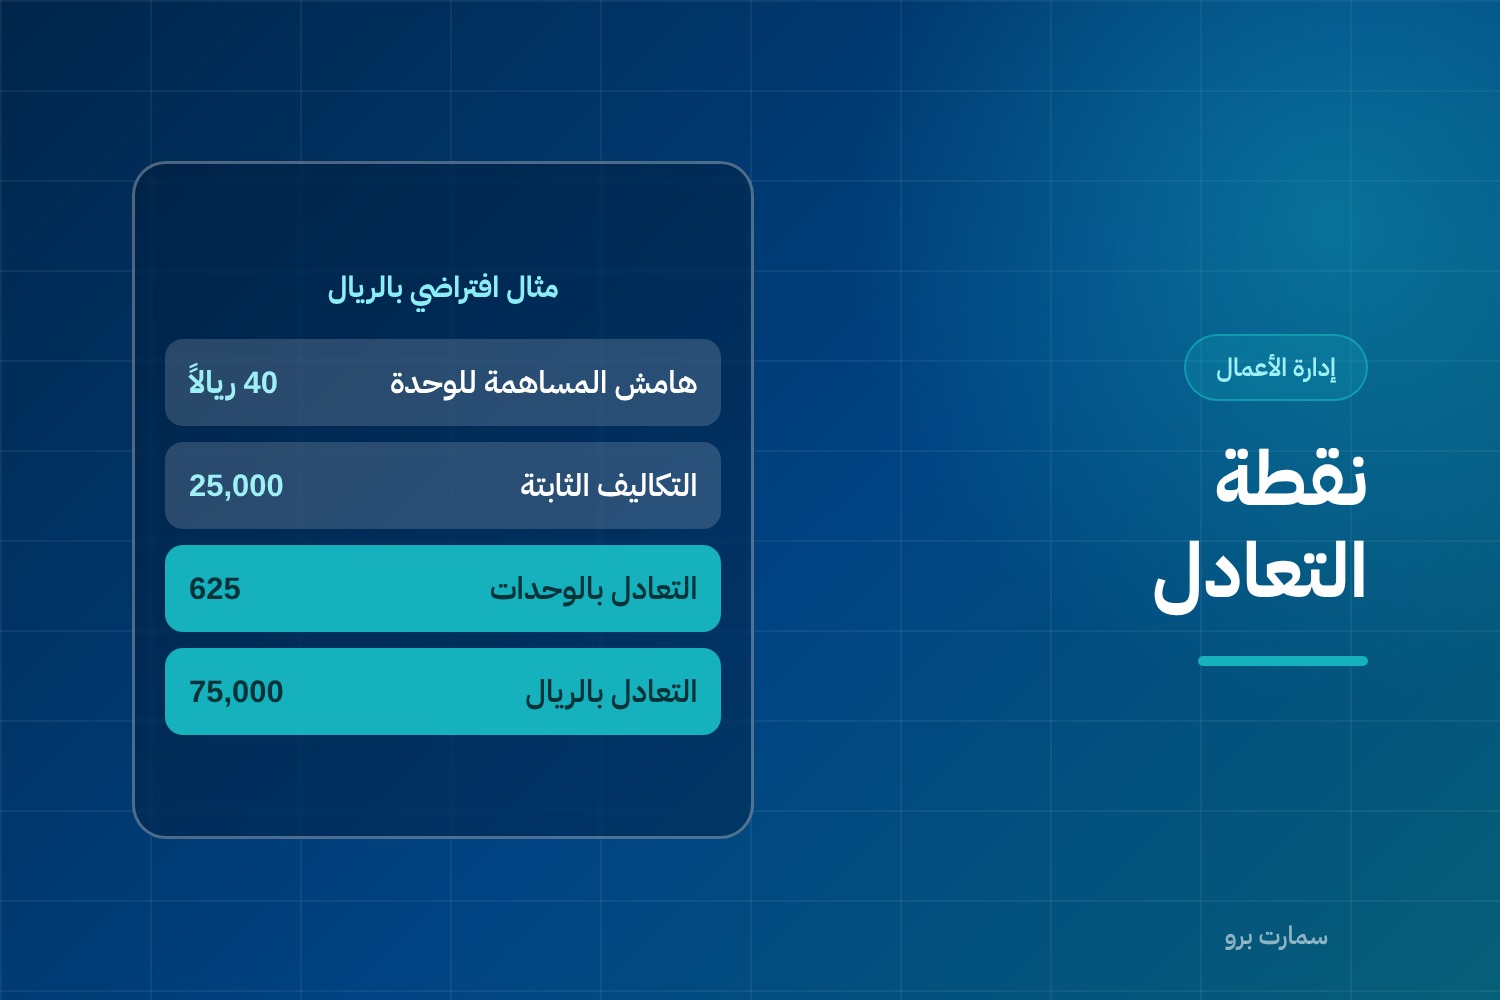
The break-even point is the sales volume at which your revenue equals your costs: no profit and no loss. It is the first number any business owner should know, because it turns the vague question "Am I doing all right?" into a measurable one: "Did I pass the number this month?"
Most people who calculate it wrongly go wrong at one step: splitting their costs.
What is the break-even formula, and what does it need first?
Break-even point in units = Fixed costs ÷ Contribution margin per unit
The contribution margin per unit is the selling price minus the variable cost per unit. In other words, it is what each unit sold contributes towards covering fixed costs and then towards profit.
To calculate in riyals: Break-even point in SAR = Fixed costs ÷ Contribution margin ratio, where the contribution margin ratio = contribution margin ÷ selling price.
The precondition comes before any calculation: every cost must be split into fixed and variable.
- Fixed costs do not change with activity volume in the short term: rent, basic salaries, subscriptions, insurance and depreciation.
- Variable costs change with every unit: cost of goods sold, commission, packaging and electronic payment fees.
The split is not always clean. A factory's electricity bill has a fixed part for lighting and a variable part that moves with the production line. A salesperson's pay has a fixed basic salary and a variable commission. These are mixed costs: they are broken into their parts, not thrown entirely into one column.
What does a break-even calculation look like in SAR?
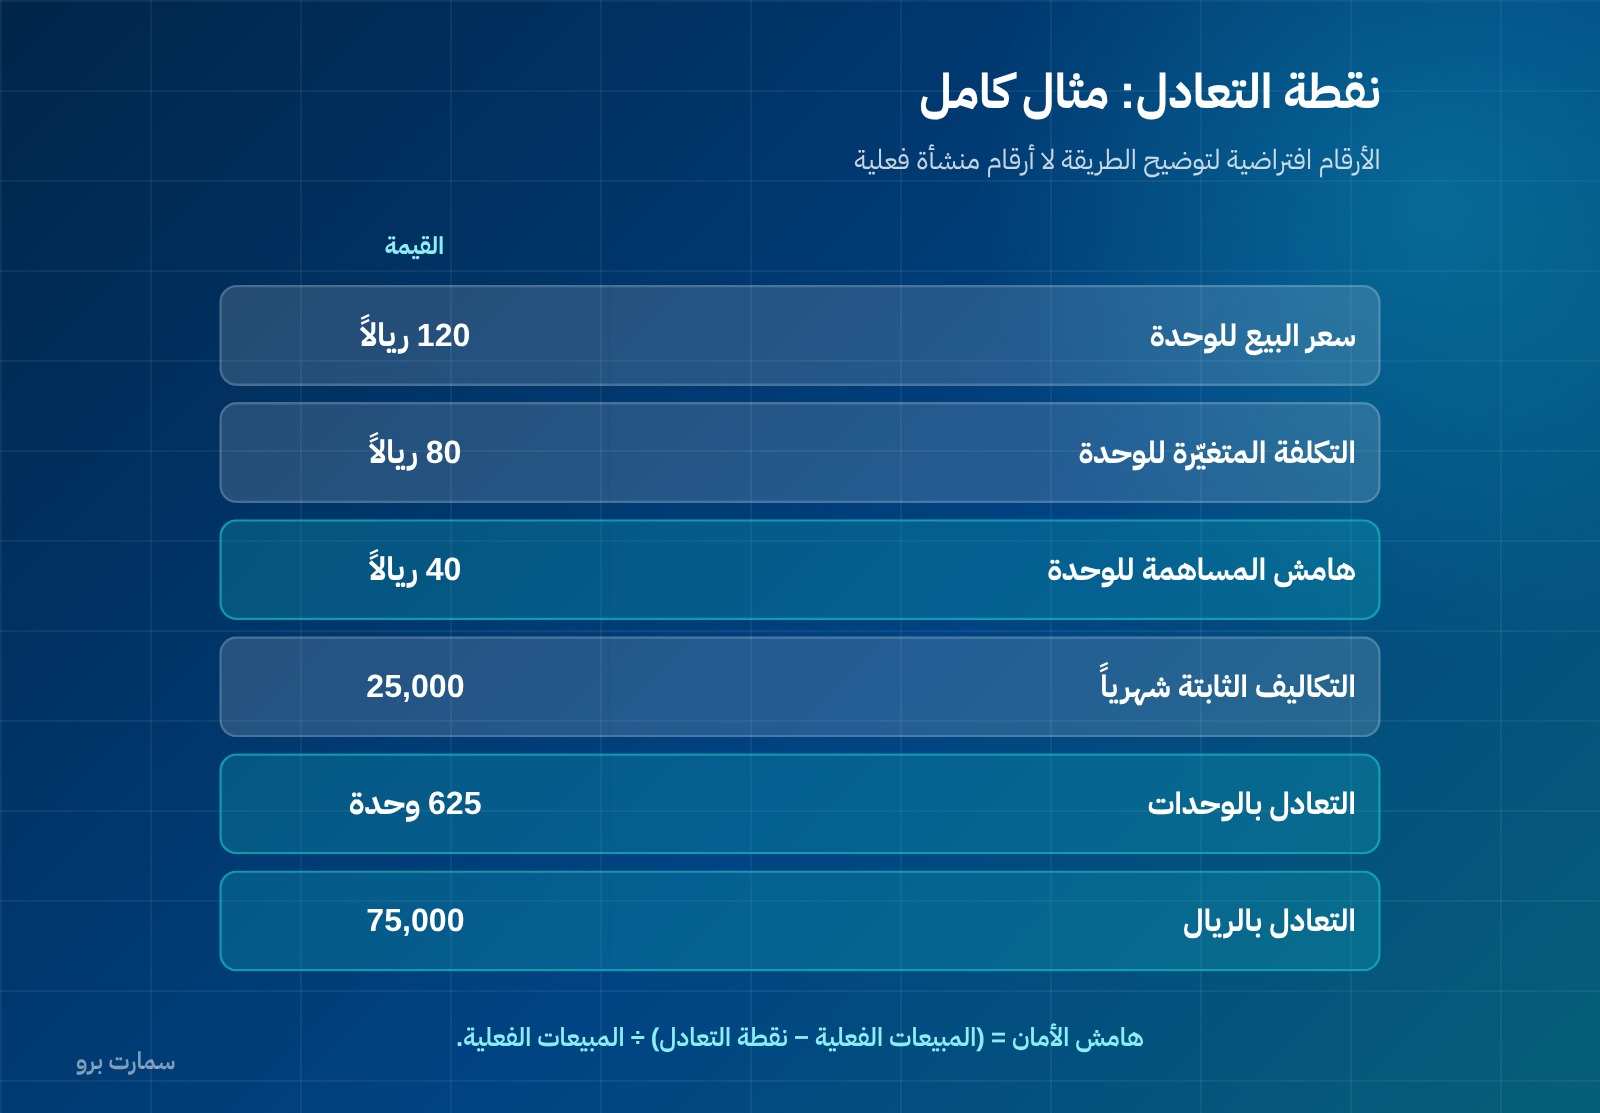
The figures below are hypothetical, to illustrate the method; they are not the figures of a real business. A shop sells one product:
| Item | Amount |
|---|---|
| Selling price per unit | SAR 120 |
| Purchase cost per unit | SAR 70 |
| Packaging and delivery per unit | SAR 8 |
| Electronic payment fees per unit | SAR 2 |
| Contribution margin per unit | SAR 40 |
| Monthly rent | SAR 9,000 |
| Basic salaries | SAR 14,000 |
| Subscriptions and fixed electricity | SAR 2,000 |
| Total fixed costs | SAR 25,000 |
Break-even point in units = 25,000 ÷ 40 = 625 units a month Break-even point in SAR = 625 × 120 = SAR 75,000
Or using the ratio: contribution margin 40 ÷ 120 = 33.33%, and 25,000 ÷ 0.3333 = SAR 75,000. The result is the same.
So every unit above 625 adds SAR 40 of profit, and every unit below it takes away SAR 40.
What is the margin of safety, and why does it matter more?
The break-even point tells you where the edge is. The margin of safety tells you how far you are from it:
Margin of safety = (Actual sales − Break-even sales) ÷ Actual sales
If the shop sold SAR 90,000: (90,000 − 75,000) ÷ 90,000 = 16.7%. That means if its sales fell by more than a sixth, it would slip into a loss. This is a narrow figure, and it says the business is sensitive to any slowdown.
If it sold SAR 150,000, the margin would be 50%, which is a comfortable position.
How many units do you need to reach a target profit?
Use the same formula, adding the profit to fixed costs:
Units required = (Fixed costs + Target profit) ÷ Contribution margin per unit
To make SAR 10,000 profit a month: (25,000 + 10,000) ÷ 40 = 875 units. That is 250 units above break-even, which is far clearer than a vague goal such as "we want to grow sales".
How can you lower your break-even point?
Each route moves one side of the formula:
- Raise the price. Raising it by just SAR 5 lifts the margin to SAR 45, and the break-even point drops to 556 units: an 11% fall from a 4% change in price. This is the strongest lever and the least used.
- Cut the variable cost. Negotiate on purchasing, or reduce packaging. A SAR 5 cut has the same effect as a SAR 5 price rise.
- Cut fixed costs. Lower rent, or cancel an unused subscription. A SAR 3,000 cut brings the break-even point down to 550 units.
- Shift the sales mix towards items with higher margins. This costs nothing, but it requires knowing the margin of each item separately.
When is the break-even point impossible to reach?
This case deserves to be stated plainly because it saves you from late decisions: the calculation may produce a number larger than your capacity.
If the break-even point is 625 units a month and the shop's maximum capacity is 500 units, the business is structurally loss-making however hard the sales team works. More effort does not fix that. Only changing one pillar of the model does: the price, the cost, the size of fixed costs, or the capacity itself.
This is the most important use of the formula: calculating it before opening the business or the branch, not after six months of losses. Four numbers (price, unit cost, fixed costs and capacity) answer the feasibility question before you sign the lease.
What is the most common mistake in the calculation?
Putting the owner's salary in the wrong place, or leaving it out altogether.
Many small business owners do not include their own pay in fixed costs, so the break-even point comes out low and reassuring. It is not correct: if you hired someone to do your job, you would pay them. By leaving this item out, you compare your business with a job that pays nothing, and you may stay for years in a venture that gives you less than a salary.
Include a market wage for yourself in fixed costs, then calculate. The number that comes out is the real one.
A second, lighter mistake: charging the whole month's inventory purchases as a variable cost. The variable cost is the cost of what was sold, not what was bought. The difference between them is inventory, and reading it requires a perpetual inventory system.
What are the limits of break-even analysis?
The break-even point is a powerful tool under certain conditions, and ignoring them leads to wrong decisions:
- It assumes constant price and cost across all volumes. That does not hold if you give volume discounts or buy on tiered purchase prices.
- It assumes one product or a fixed mix. With several products, you calculate a weighted contribution margin using sales weights, and the result changes as the mix changes.
- It is short term. A "fixed cost" is fixed only within a given capacity. Going beyond capacity calls for a new branch or production line, so fixed costs jump and the break-even point jumps with them.
- It does not measure cash. You can pass break-even on paper and still struggle for cash if your receivables are not collected. That is why it should be read alongside the statement of cash flows.
How do you keep the break-even point up to date?
The break-even point is not a one-off calculation. Make it part of your monthly cycle:
- Classify your expense accounts as fixed or variable once, in your chart of accounts.
- Calculate the point from your actual income statement figures, not from an estimate.
- Review it every quarter, and immediately after any change in rent, salaries or purchase prices.
- Show it as a line on your monthly sales report, so the people who sell see it, not just the accountant.
For tailoring and dressmaking businesses, see how this applies to that trade in break-even for a tailoring shop.
The principles for measuring costs and presenting performance in financial statements are set by the International Financial Reporting Standards.
Key takeaway: Split your costs into fixed and variable, include a market wage for yourself, and divide fixed costs by the contribution margin per unit. Then track your margin of safety every month and calculate the point before opening any new branch.
If you want your sales, costs and income statement figures in one connected system, you can start a SmartPro free trial.
Article visuals
Frequently asked questions
What is the break-even point formula?
Break-even point in units = fixed costs ÷ contribution margin per unit, where the contribution margin is the selling price minus the variable cost per unit. In riyals, it is fixed costs ÷ contribution margin ratio. The precondition is that all costs are first split into fixed and variable.
What is the difference between fixed and variable costs?
Fixed costs do not change with activity volume in the short term, such as rent, basic salaries, subscriptions, insurance and depreciation. Variable costs change with every unit, such as cost of goods sold, commission, packaging and electronic payment fees. There are also mixed costs, such as electricity and a salesperson's pay, which are split into their two parts rather than put entirely in one column.
What is the margin of safety and how is it calculated?
It is how far your sales are from the break-even point, calculated as (actual sales − break-even sales) ÷ actual sales. Sales of SAR 90,000 with a break-even point of SAR 75,000 give a margin of 16.7%. That means a fall in sales of more than a sixth would push the business into a loss.
How can I lower my break-even point?
There are four ways: raise the price, cut the variable cost per unit, cut fixed costs, and shift the sales mix towards higher-margin items. Raising the price is the strongest lever and the least used. A 4% price rise can lower the break-even point by 11%.
What are the limits of break-even analysis?
It assumes constant price and cost across all volumes, so it does not hold with volume discounts. It assumes one product or a fixed mix, so several products require a weighted contribution margin. It is short term because fixed costs stay fixed only within a given capacity, and it does not measure cash: you can pass break-even on paper and still struggle for cash if your receivables are not collected.