
End-of-Service Provision: Why You Need It and How to Calculate It Monthly
An end-of-service provision prevents profits that look higher than they are, followed by a sudden loss. Here is how to calculate it monthly, the journal entries with figures, and how to treat it when an employee leaves.
سامي الحيدري
An end-of-service provision is the difference between a business that knows its obligations and one that discovers them by surprise. The end-of-service award is not an event that happens on the day an employee leaves; it is an obligation that builds up month after month throughout the employee's service.
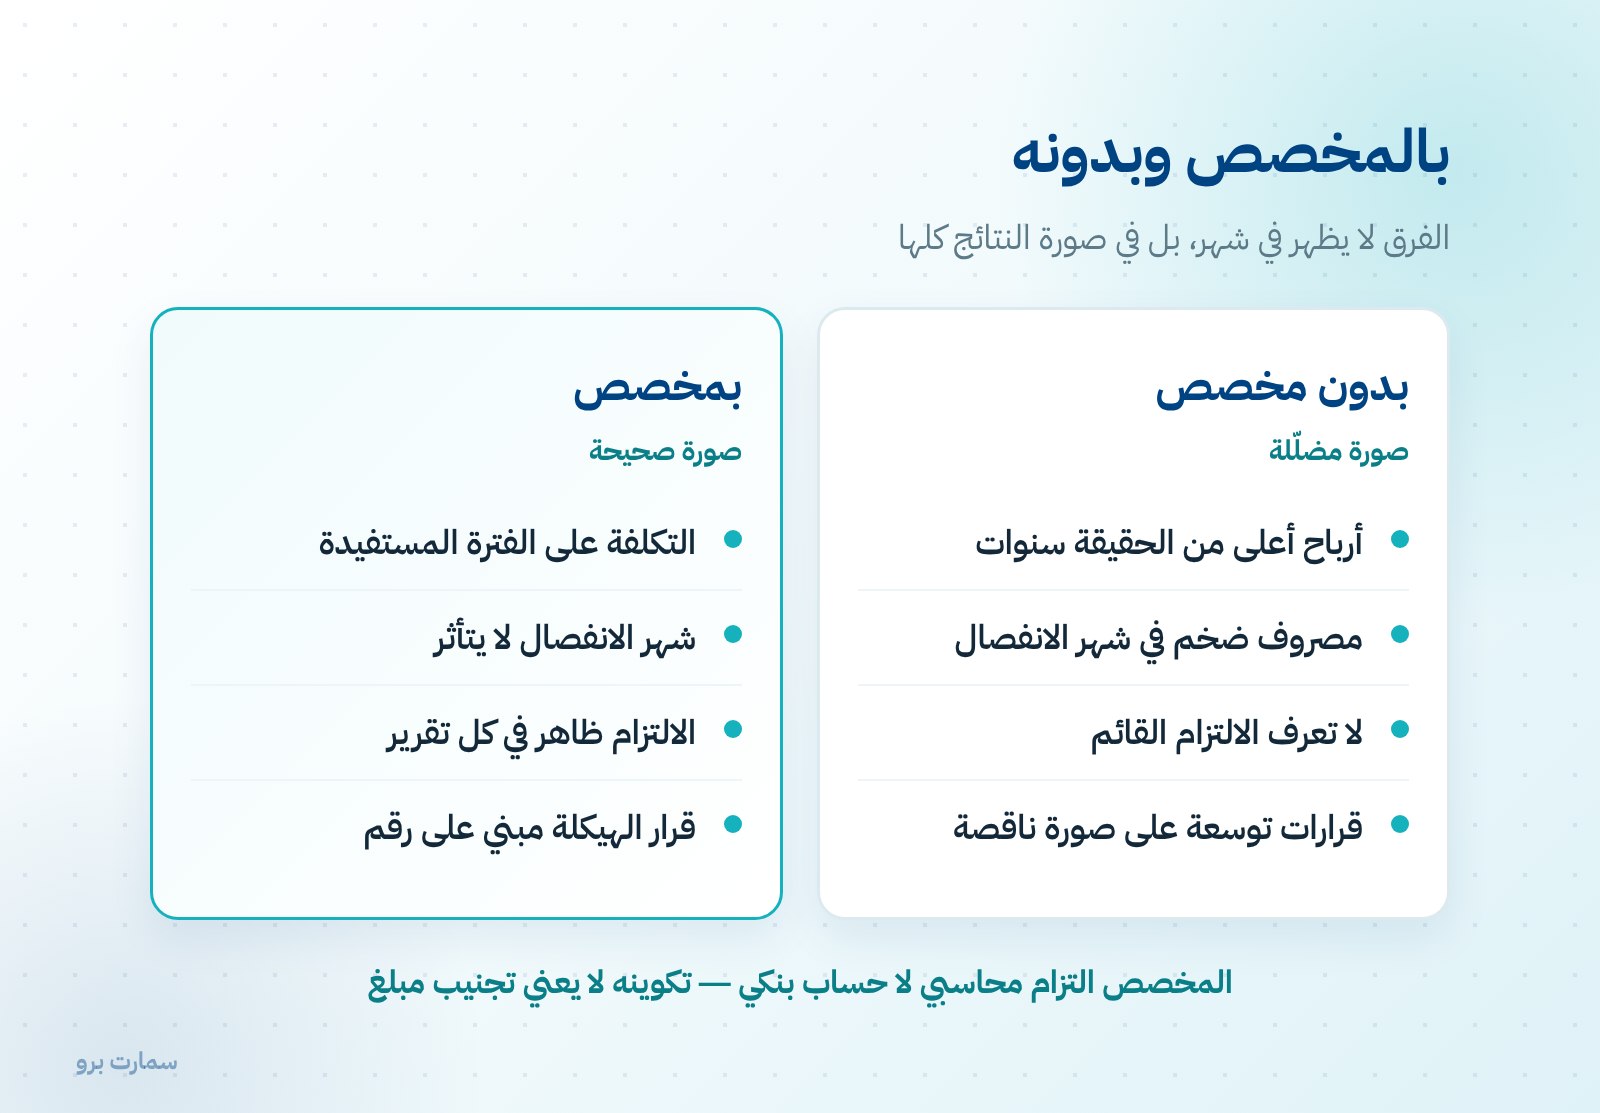
A business that does not build the provision reports profits higher than reality for years, then books a large expense in a single month that has nothing to do with that month's performance.
End-of-service provision: why is it necessary?
Picture a business with twenty employees, an average service of six years and an average wage of SAR 9,000. The award obligation it already carries is roughly:
- Per employee: (5 × 0.5 × 9,000) + (1 × 1 × 9,000) = SAR 31,500
- For all twenty: SAR 630,000
This amount is owed by the business today, even if it does not appear in its books. A decision such as an expansion or a profit distribution taken without knowing it is a decision based on an incomplete picture.
How is it calculated monthly?
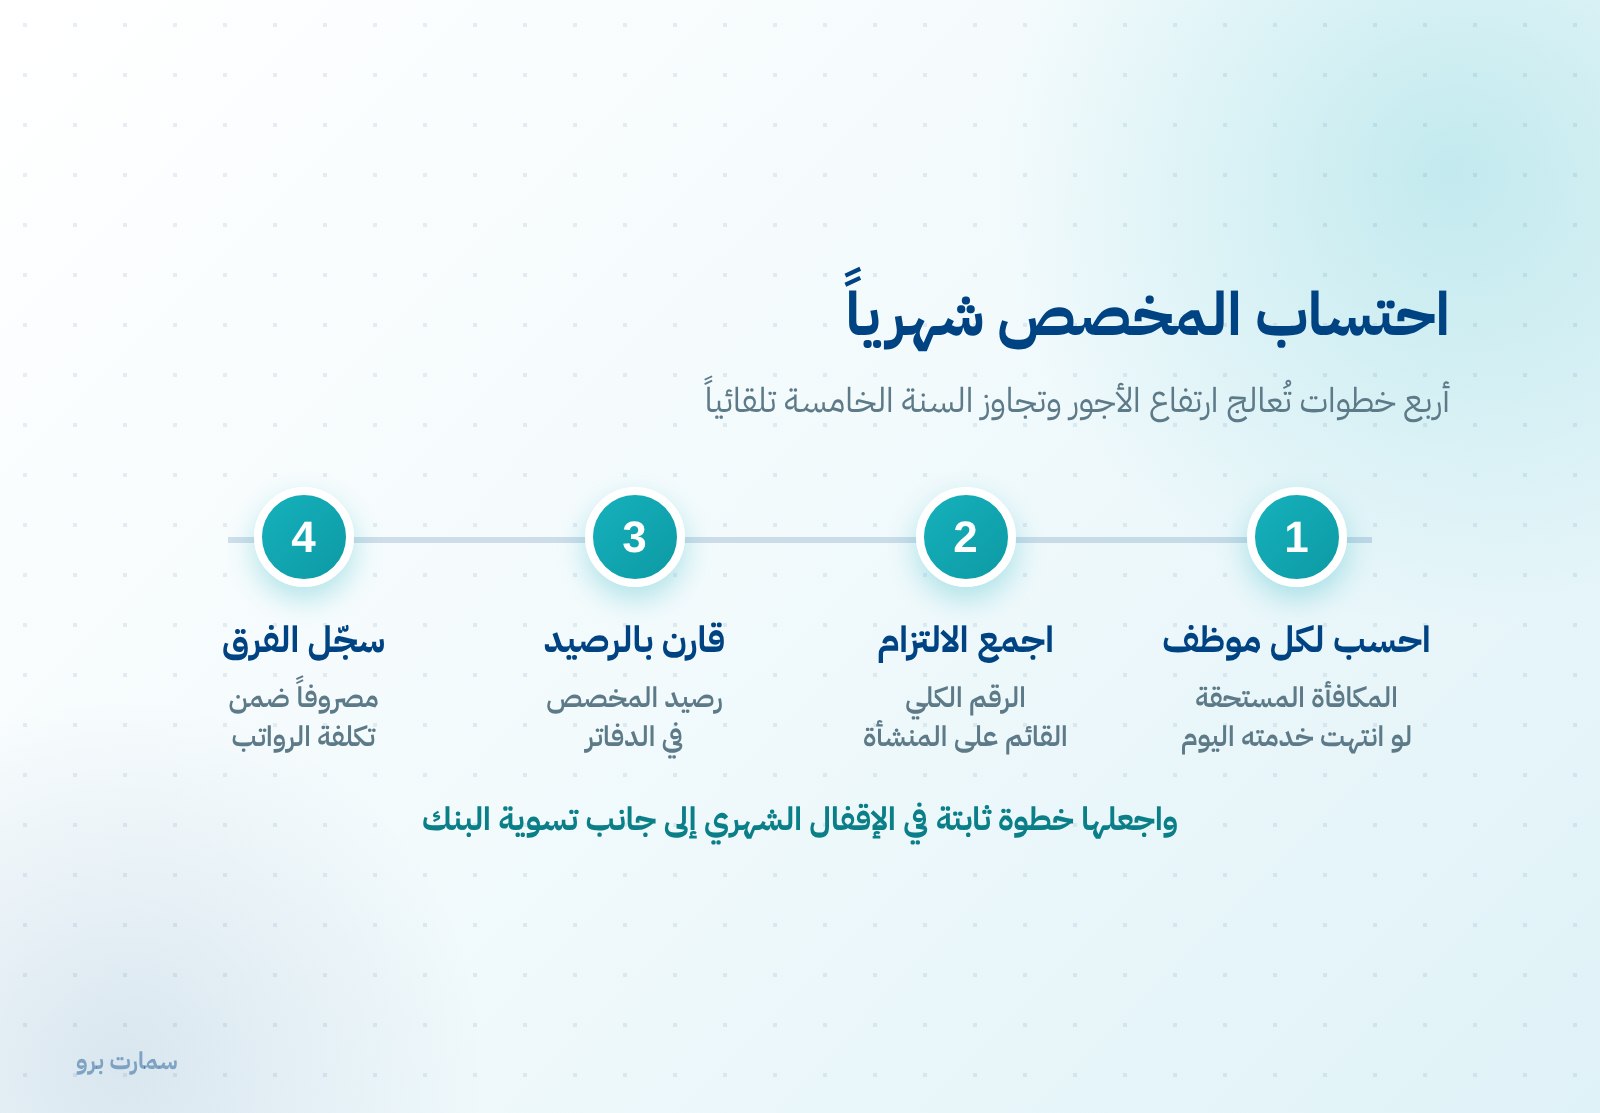
The sound method is to recalculate the total obligation at the end of each month, then record the difference between it and the current provision balance.
| Step | What it involves |
|---|---|
| 1 | Calculate the award each employee would be due if their service ended today |
| 2 | Add them up to get the total obligation |
| 3 | Compare it with the provision balance in the books |
| 4 | Record the difference as an expense within payroll cost |
This method handles two things automatically: wage increases, which raise the obligation for past years, and passing the fifth year, which doubles the entitlement factor.
A worked example
A business starts the month with a provision balance of SAR 400,000. When the obligation is recalculated at month end, it comes to SAR 412,000:
| Account | Debit | Credit |
|---|---|---|
| End-of-service award expense | 12,000 | |
| End-of-service award provision | 12,000 |
The SAR 12,000 is not arbitrary: it is one month's accrual for all employees, plus the effect of any salary increase and any employee who passed the fifth year.
The entry when an employee leaves
When an employee's service ends and their award is paid, no new expense is recorded; instead, the provision is reduced:
| Account | Debit | Credit |
|---|---|---|
| End-of-service award provision | Amount paid | |
| Bank or salaries payable | Amount paid |
This is the core benefit: the month of departure is not affected, because the cost was already charged to the months that actually benefited from the work.
If the amount paid differs from the provision, for example when an employee resigns and is entitled to only part of the award, the difference is settled by adjusting the provision up or down. See end-of-service award on resignation.
Should the provision be based on the full amount or the expected amount?
This is a matter of judgement. Two approaches are common:
- The conservative approach: calculate the full obligation as if every employee's service were terminated by the employer today.
- The adjusted approach: calculate the obligation taking into account the likelihood of resignations and their graduated rates.
The first is simpler and more conservative; the second is closer to reality but needs documented assumptions. What matters is applying the method consistently rather than switching from year to year, because switching makes comparisons between periods meaningless.
In larger businesses or those subject to audit, more detailed estimation methods are used that consider staff turnover rates and other assumptions. This is a question to settle with the auditor, not inside the payroll team.
Where does the provision appear in the financial statements?
In the statement of financial position under liabilities, usually within non-current liabilities, except for the part expected to be paid within a year.
In the income statement, its effect appears within salary expense or as a separate line, depending on how the business presents it.
Does the provision have to be funded in cash?
The provision is an accounting liability, not a bank account. Building it does not mean setting money aside.
But a business with a large obligation and no liquidity behind it faces a real problem when a wave of departures comes. That is why some businesses choose to actually set aside part of the amount, which is a management decision, not an accounting requirement.
Five signs your treatment is wrong
- The award expense only appears in months with departures.
- The provision balance has not changed for months even though employees are still working.
- You only know the outstanding obligation through a manual calculation that takes a day.
- Salary increases are not reflected in the provision.
- There is no report showing the obligation per employee.
How do you make it a monthly routine?
Make recalculating the obligation a fixed step in the month-end close, alongside bank reconciliation and receivables matching. A system that calculates each employee's award from their start date and current wage turns this step into a report you can pull in a minute.
The benefit goes beyond the books: knowing the outstanding obligation before any restructuring or downsizing decision sometimes changes the decision itself. See the accounting cycle steps and the payroll journal entry.
The difference between a provision and a reserve
The two terms are often confused. A provision is an estimate of an existing obligation whose cause is known but whose exact amount is not, and building it is mandatory because the obligation already exists. A reserve is an allocation from profits for a future purpose, and creating it is a decision for the owners.
The end-of-service award is clearly the first type: the employee works today, the right arises today, and only the amount is estimated. That is why it is not acceptable to postpone building it on the grounds that profits do not allow it.
What if the business never built one?
A business that has operated for years without a provision faces a practical question: should it charge the whole obligation to a single year?
The correction is to recognise the full outstanding obligation and treat the effect of prior years according to the accounting standards the business applies, in coordination with its auditor. The key is not to delay the correction further, because the gap widens every month.
The official reference
The rules for end-of-service award entitlement on which the provision is based are set out in the Labour Law published by the Ministry of Human Resources and Social Development. How the provision is measured and presented in the financial statements is determined by the accounting standards the business applies and agreed with its auditor.
Read also
Frequently asked questions
What is an end-of-service provision?
It is an accounting liability built up monthly to reflect the end-of-service award employees have earned for the time they have actually worked. Its purpose is to charge the cost to the periods that benefited from their work, instead of having it appear all at once in the month they leave.
How is the end-of-service provision calculated monthly?
Recalculate the award each employee would be due if their service ended today, add them up to get the total obligation, then compare it with the provision balance and record the difference as an expense. This method automatically handles wage increases and employees passing the fifth year.
What is the journal entry when the award is paid?
No new expense is recorded; the provision is reduced instead, with the end-of-service award provision debited and the bank credited. The month of departure is not affected because the cost was already charged earlier. If the amount paid differs from the provision, the difference is settled by adjusting the provision.
Do you have to set cash aside for the provision?
No. The provision is an accounting liability, not a bank account, and building it does not mean setting money aside. However, a business with a large obligation and no matching liquidity faces a real problem when a wave of departures comes, so some businesses choose to set cash aside as a management decision.