
Input VAT Deduction: What You Can Claim, What You Can't, and How to Prove It
The conditions for deducting input VAT, the cases where it is not allowed, how to handle mixed taxable and exempt activity, and the mistakes that cost you the deduction at audit.
Author:سامي الحيدري
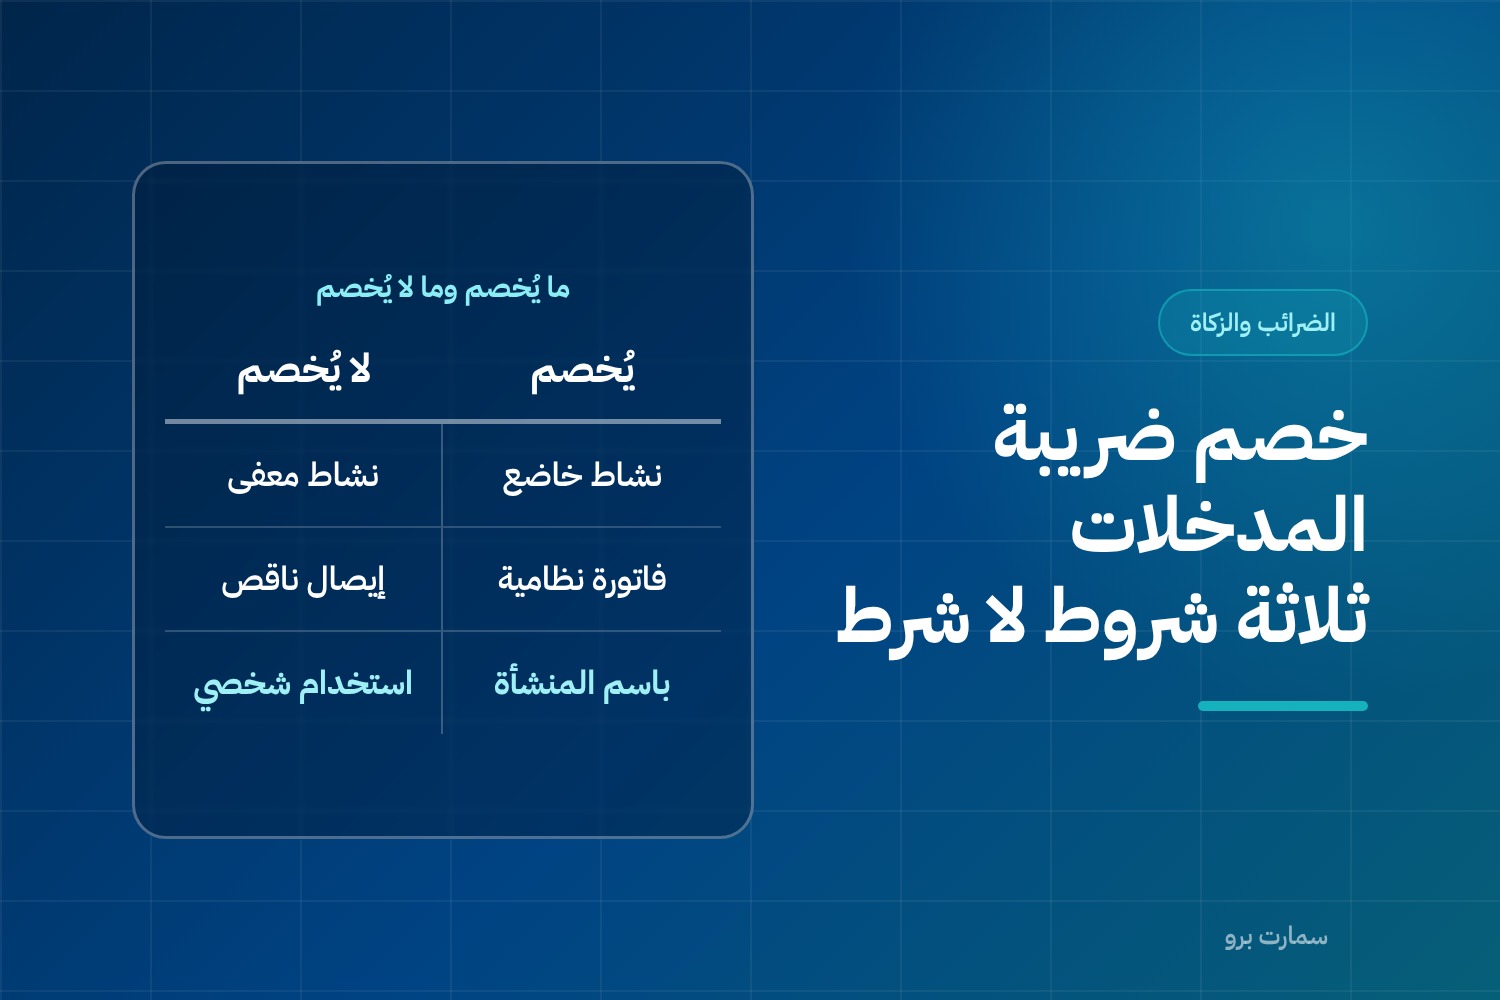
Input VAT deduction means subtracting the VAT you paid suppliers from the VAT you charged customers, so you remit only the difference to ZATCA. You can deduct it when three conditions are met together: you are VAT-registered, the purchase serves your taxable activity, and you hold a compliant tax invoice. Miss one and the deduction fails.
This is what makes VAT a tax on value added rather than on total sales. You collect 15% from your customer, pay 15% to your supplier, and remit the difference. When part of your input VAT is rejected at audit, you lose more than paperwork: you pay tax out of your profit on value you never added. This guide covers the conditions, the cases where the deduction is refused, and how to prove your right to it.
What are the conditions for deducting input VAT?
The deduction is not automatic just because an invoice shows VAT. Input VAT is the VAT charged to you on purchases; output VAT is the VAT you charge on your sales. As a general rule, input VAT is deductible when three things are true together:
You are registered. An unregistered business cannot deduct; the VAT it pays becomes part of its cost. Incidentally, this is one reason registration can lower the real cost for a business with large purchases, as explained in VAT registration in Saudi Arabia.
The purchase is for your taxable activity. Anything bought for personal use or for an exempt activity is not deductible. What counts is the actual purpose, not the buyer's name on the invoice.
You keep a compliant tax invoice. The invoice is your evidence for the deduction. An invoice missing the required details, such as the supplier's VAT number or the VAT breakdown, is not sufficient evidence. See tax invoice requirements.
When is input VAT not deductible?
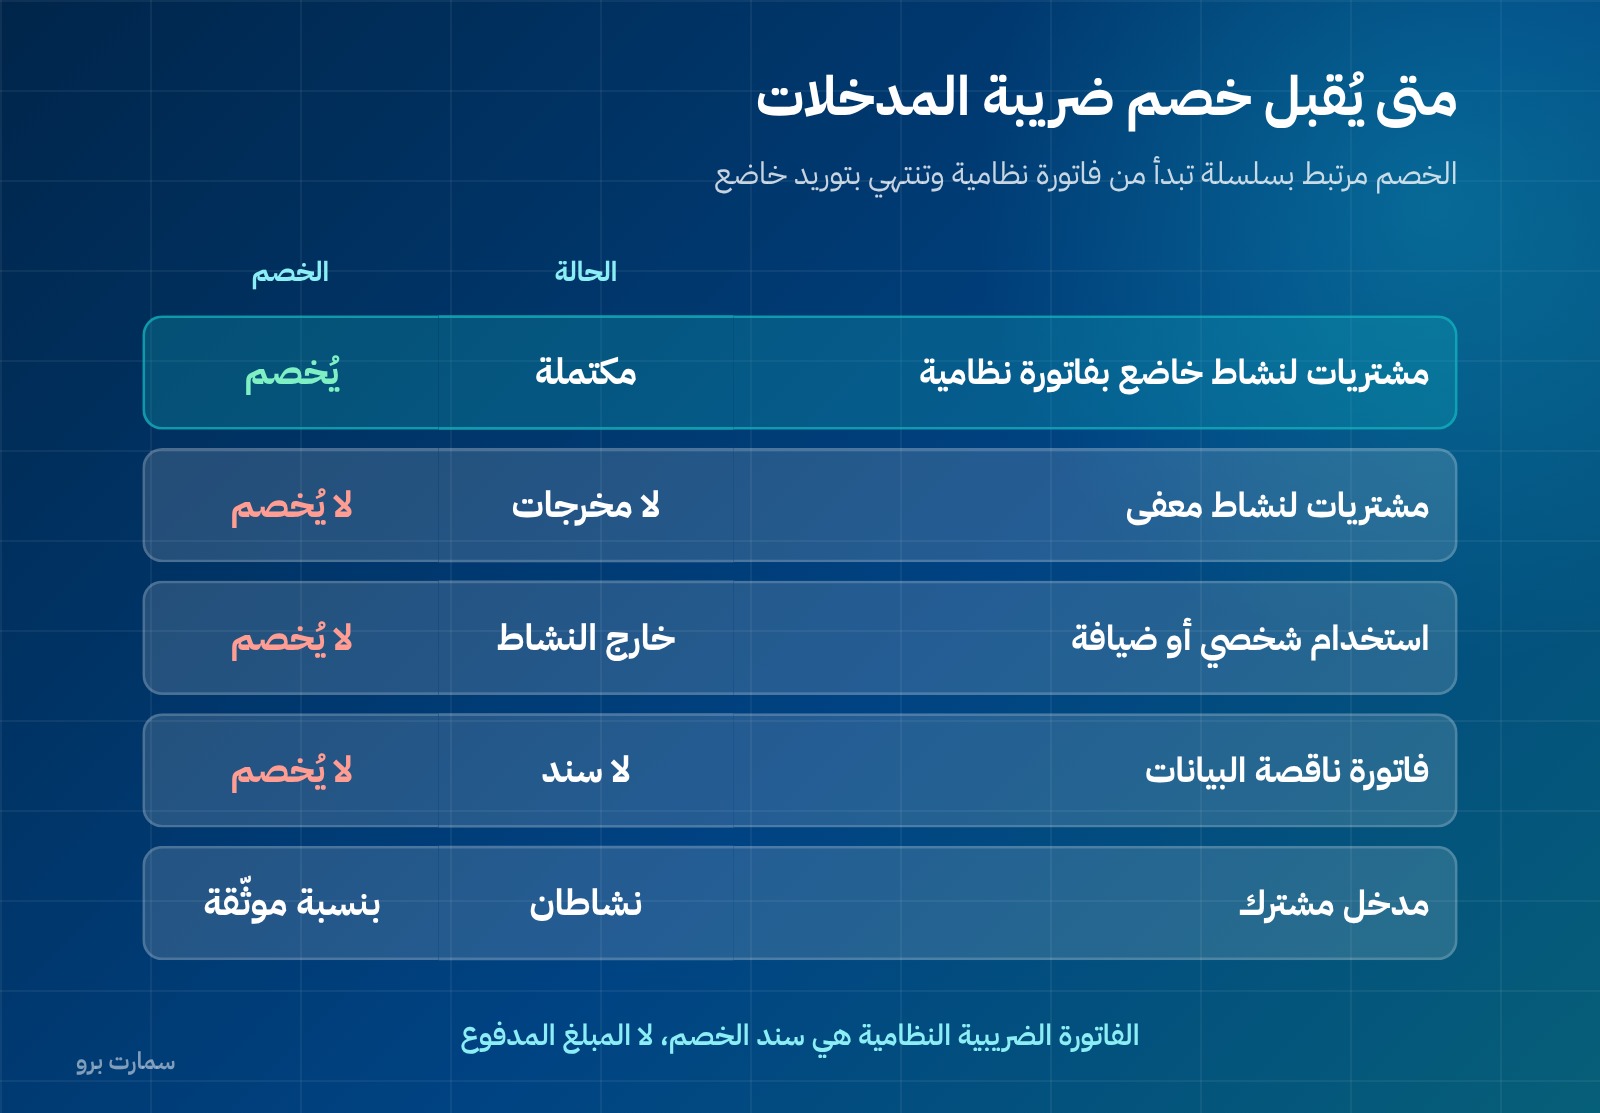
This is where audit findings come up again and again:
| Case | Reason |
|---|---|
| Purchases for an exempt activity | They produce no output VAT to deduct from |
| Personal or family use | Not for business purposes |
| Hospitality and entertainment | Consumption in nature; does not directly serve a taxable supply |
| Invoice without the required details | No evidence for the deduction |
| Invoice in another person's name | The business is not the one bearing the VAT |
| Amount paid but no invoice received | Not deductible before the evidence exists |
The rule behind all of them: the deduction depends on a clear chain that starts with a compliant invoice and ends with a taxable supply. Any missing link breaks the deduction.
How do you handle mixed taxable and exempt activity?
If your business has two activities, one taxable and one exempt, you cannot deduct all your input VAT. There are three cases:
- Input serving only the taxable activity: fully deductible.
- Input serving only the exempt activity: not deductible.
- Shared input (one office rent, electricity, an accounting system): deductible in proportion, using a fair basis that reflects how much the input is used in the taxable activity.
The common practical mistake here is not the ratio itself but having no separation at all. A chart of accounts, the structured list of accounts your books are kept in, that does not separate taxable from exempt revenue turns any ratio into an estimate you cannot defend. Separation starts with building your chart of accounts, and the difference between exempt and zero-rated is explained in exempt vs zero-rated supplies. That difference matters here: zero-rated supplies allow deduction, exempt supplies do not.
Which mistakes cost you the deduction?
Consolidated statements without detail. A supplier sends a monthly statement of account instead of invoices. A statement is not a tax invoice.
Small cash receipts with no VAT number. Small, frequent expenses add up to a large amount, and all of it is non-deductible because the evidence is incomplete.
Deducting VAT on an invoice not recorded in its period. The deduction follows the correct period. Recording a March invoice in May creates a gap between your return and your books.
Deducting on capital purchases without tracking. An asset used partly for a non-taxable purpose needs treatment that tracks its use, not a full deduction in the month of purchase.
Not recording credit notes. When a supplier gives you a later discount through a credit note, the input VAT you deducted must fall by the same amount. Details are in credit and debit notes.
How do you prove your right to the deduction?
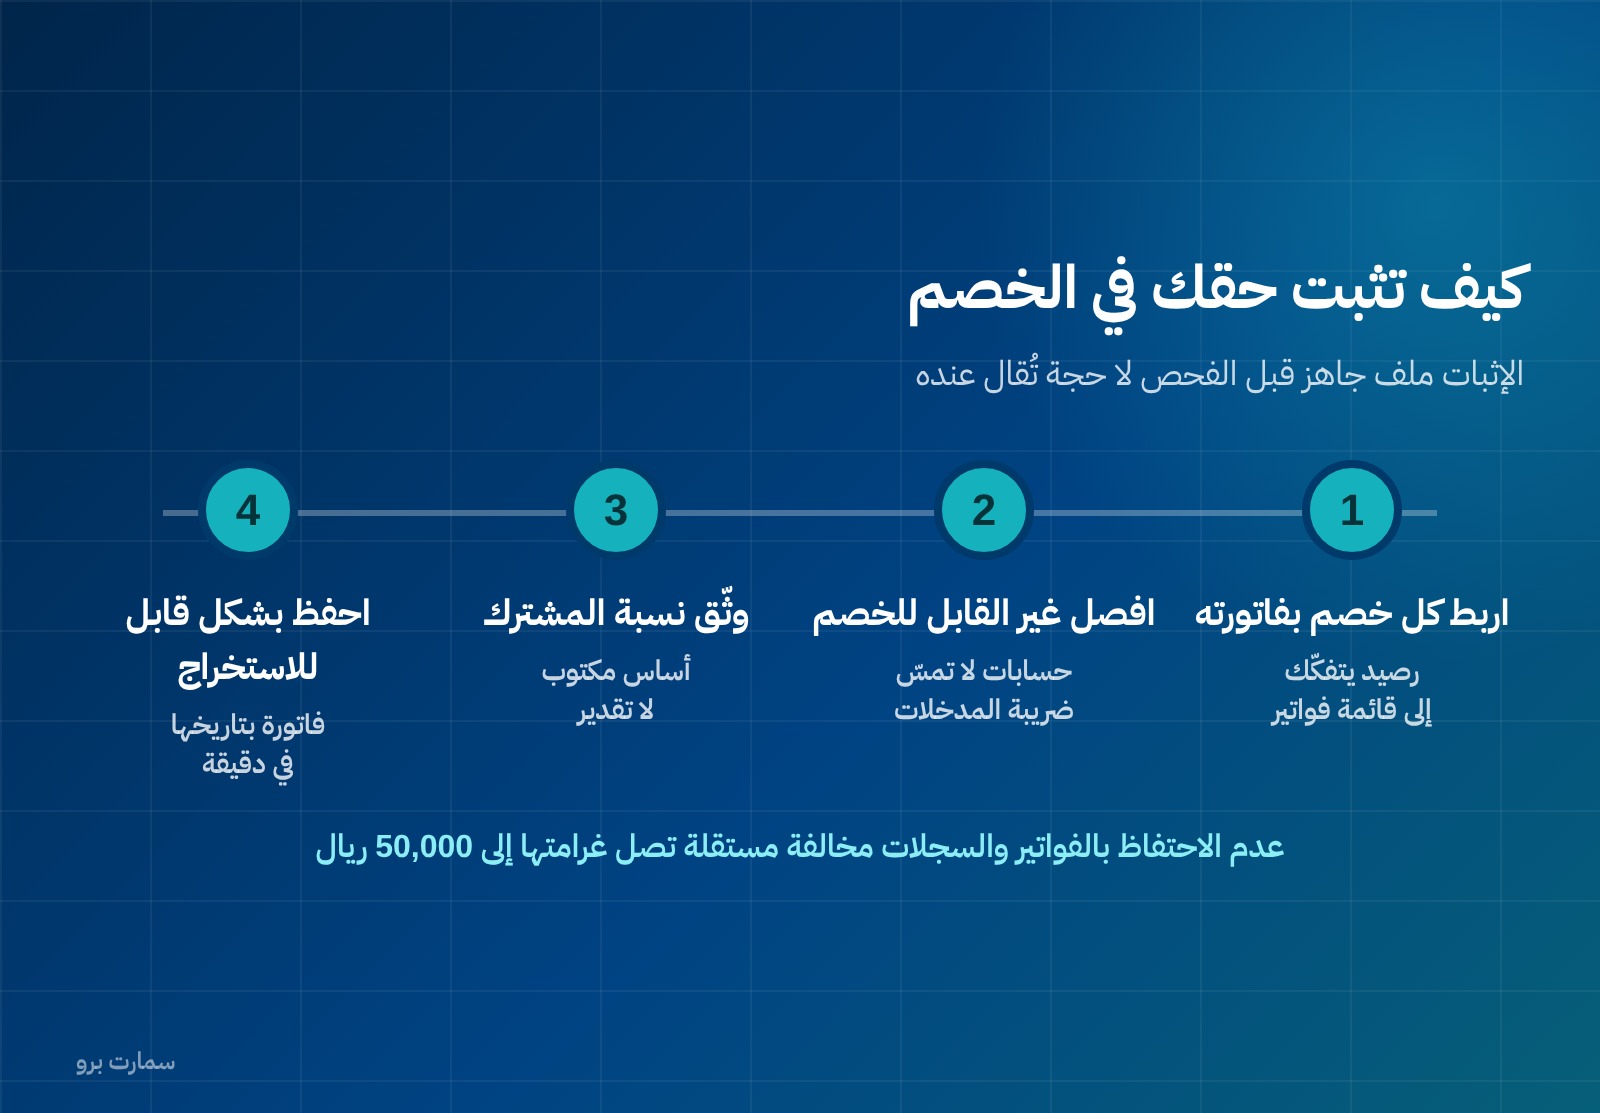
Proof is not an argument you make during the audit; it is a file that is ready before it. Three things make your file solid:
Link every deduction to its invoice in the system. If the input VAT balance in your trial balance breaks down into a list of invoices with their numbers, dates and suppliers, you have proof. If it is a manually entered figure, you don't.
Keep invoices in a retrievable form. Failing to keep invoices, books and records is a separate violation with a fine of up to SAR 50,000, independent of the rejected deduction itself.
Have a written policy for non-deductible expenses. Hospitality, personal use and purchases for exempt activity should post automatically to accounts that never touch the input VAT account, not depend on the accountant's judgement each time.
What should you check at the end of each period?
- Every amount in the input VAT account has a compliant tax invoice attached.
- No invoices in the name of anyone other than the business sit in the account.
- Hospitality and personal-use expenses are posted to separate accounts.
- The deduction ratio for mixed activity is calculated on a documented basis, not an estimate.
- Supplier credit notes are recorded and their effect on input VAT is reversed.
- Amounts paid without an invoice received have not been deducted yet.
- The account balance matches the total of deductible purchase invoices for the period.
A business that keeps these seven in order gets through an audit without negotiation. One that deducts based on the amount paid rather than a compliant invoice ends up paying VAT out of its profit.
Where is the official reference?
The Zakat, Tax and Customs Authority (ZATCA) publishes the deduction rules and record-keeping penalties in its regulations and guidelines on its website: zatca.gov.sa. Treatment differs for some sectors, and the sector-specific guideline is the reference where they differ.
Read also
Key takeaway: Input VAT is deductible only when registration, taxable purpose and a compliant tax invoice all line up; keep every deduction linked to its invoice so your file is ready before the audit.
To see how purchase invoices post to the input VAT account automatically, start a free trial of SmartPro.
Article visuals
Frequently asked questions
What are the conditions for deducting input VAT?
Three conditions must be met together: you are registered for VAT, the purchases are for your taxable activity, and you keep a compliant tax invoice with complete details proving the VAT paid. If any condition is missing, the deduction fails, even if the amount was actually paid.
Can I deduct input VAT on an exempt activity?
No. Inputs that serve an exempt activity are not deductible because they produce no output VAT to deduct from. Inputs shared between a taxable and an exempt activity are deductible in proportion, using a fair, documented basis. Note that zero-rated is different from exempt: zero-rated supplies allow deduction.
Is a cash receipt enough to deduct input VAT?
Not if it lacks the required details. The evidence for the deduction is a tax invoice that meets the requirements, including the supplier's VAT number and the VAT breakdown. Small, frequent receipts with no VAT number add up to a large non-deductible amount at audit.
What happens if a supplier gives me a discount after I have deducted the VAT?
You must record the credit note and reduce the input VAT you deducted by the same amount. Keeping the original deduction unchanged after receiving a credit note creates a difference that shows up at audit and is handled in the corrections section of the VAT return.